Climate technology has gone from fashionable to unfashionable and, in the age of artificial intelligence, back again — though not in the way many climate investors expected.
Fundraising for climate-specialist venture capital firms in 2025 was down nearly 40% from 2024, according to PitchBook data cited by Fortune on Wednesday, September 23. Yet at Climate Week NYC this week, investors described a market in which startups in energy and related fields are attracting significant capital — much of it from generalist investors drawn by the power demands of AI.
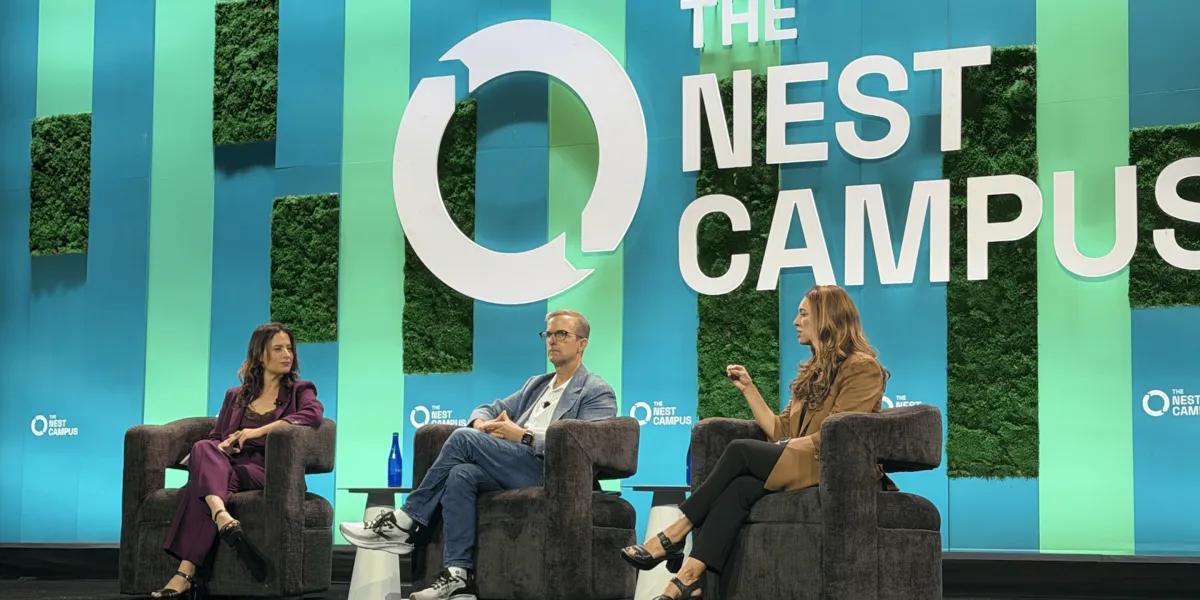
Fortune’s Term Sheet editor, Allie Garfinkle, discussed the shift on stage at The Nest Campus, the Climate Week NYC hub at the North Javits Center, with Dawn Lippert, founder and chief executive of Elemental Impact and a general partner at Earthshot Ventures, and Mike Schroepfer, former chief technology officer of Meta and founding partner of Gigascale Capital.
AI as a tailwind
The rapid growth of AI has transformed the conversation around energy. Data centres that train and run AI models require enormous amounts of electricity, and developers are searching for power sources that can be deployed quickly and reliably.
“AI I think is both a headwind and tailwind for the space, but more a tailwind than a headwind,” said John MacDonagh, senior research analyst at PitchBook, in comments to Fortune.
MacDonagh explained that data-centre developers are looking for energy sources to support their projects. Renewables can be fast to deploy and relatively low-cost but face intermittency challenges that can be addressed by energy storage, he said, while firm power sources may be better suited to data centres but are less mature and require substantial funding to develop and commercialise.
That creates opportunities across the energy-technology stack — from solar, wind and batteries to next-generation firm power such as advanced nuclear and geothermal, as well as grid technologies that allow existing infrastructure to carry more power.
Generalists fill the gap
The decline in climate-specialist fundraising has not meant a collapse in funding for climate-related startups. Instead, generalist investors have increasingly stepped in.
“90% of the companies that Earthshot backs have generalist tech investors as our co-investors,” Lippert said, according to Fortune. She argued that climate investors still play an important role on cap tables: “We think it’s really helpful to be a climate investor on the cap table of these companies, asking about social impact, asking about environmental impact, sometimes we’re the only ones in the room asking those questions.”
Schroepfer, who raised $250 million for a climate-focused fund announced in June, said he had been asked to consider rebranding it as an AI fund but declined, according to Fortune. He described a similar pattern of co-investment from generalists and follow-on investors.
A tale of two markets
Schroepfer characterised the market as a tale of two cities. “If you’re in the energy space, critical minerals, anything that’s supply chain, there’s more money than I’ve ever seen from an investing standpoint to do that work,” he said.
That divide is significant. Startups that can position themselves as solutions to the power needs of AI and the resilience of industrial supply chains are finding capital relatively accessible. Those focused on climate priorities less directly linked to those themes — such as some areas of agriculture, consumer sustainability or carbon removal — may face a tougher fundraising environment.
The broader numbers
Other data point to a market that has stabilised rather than collapsed. Dealroom estimates that funding into climate-tech startups reached $39 billion in 2025 and that $19.5 billion was raised in the first half of 2026, putting the full year on track for a similar total — nearly ten times the level of five years earlier.
Individual climate funds are still being raised. Climate-focused venture firm Pulse Fund, founded by climate-tech entrepreneur Tenzin Seldon, announced the close of its inaugural $63 million fund this month to back early-stage companies across energy transition, infrastructure, food and agriculture, and mobility, ESG Today reported.
Large infrastructure investors are also active. On the same day as the Fortune discussion, Ares announced the acquisition of an 80% stake in a 384 MW California solar-and-storage portfolio from EDP Renewables, valued at about $0.8 billion.
The divergence is also visible in the kinds of companies raising the largest rounds, which are increasingly concentrated in firm power, grid infrastructure and energy storage.
Women leading climate capital
The conversation also highlighted the prominent role of women in climate investing. Lippert has built Elemental Impact into a significant platform for climate innovation and co-leads investment at Earthshot Ventures, while founders such as Tenzin Seldon are launching new funds. Climate Week NYC featured dedicated gatherings for female venture investors and startup operators across energy, AI, mobility, resilience and infrastructure.
What it means for founders
For climate founders, the message is pragmatic. Framing a company around energy, power, grid capacity, critical minerals or supply-chain resilience may resonate more strongly with today’s investors than framing it purely around emissions reduction. Many investors increasingly see decarbonisation and energy security as overlapping goals.
At the same time, relying on generalist investors carries risks. Generalists may be less patient with long development timelines and less familiar with the technical and regulatory complexities of climate hardware — a reason specialists such as Lippert argue that climate expertise remains valuable on cap tables.
The India angle
The same forces are at work in India, where data-centre construction is accelerating and electricity demand is rising quickly. Indian climate-tech startups in energy storage, grid technologies and clean manufacturing may find that the AI-driven power narrative helps attract investors, while those in areas such as sustainable agriculture or circular economy may need to demonstrate strong commercial fundamentals to secure capital.
The bottom line
The climate-investing landscape of 2026 looks very different from the boom of a few years ago. Dedicated climate funds are harder to raise, but energy innovation is attracting substantial capital as the world confronts the power demands of AI. As Lippert and Schroepfer’s comments suggest, the energy transition may be advanced less by climate-branded capital than by investors chasing the economic opportunity of powering the digital economy.