ImpactSustainability5 MIN READ

Horizons Clean Energy India Opens in New Delhi as Green Hydrogen Ambitions Meet Execution Reality

More than 200 policymakers and industry leaders gather in New Delhi on September 24–25 for Horizons Clean Energy Expansion India 2026, as India’s green hydrogen mission confronts a wide gap between awarded and commissioned capacity.

By Nisha Omkumar · Author24 September 2026Event
Horizons Clean Energy India Opens in New Delhi as Green Hydrogen Ambitions Meet Execution Reality

More than 200 policymakers and industry leaders are gathering in New Delhi on September 24 and 25 for Horizons Clean Energy Expansion India 2026, a two-day forum focused on turning India’s clean-energy ambitions into commercially viable projects, according to the event organisers.

The event — formerly known as World Hydrogen India — is being convened by S&P Global Energy, according to a report by The Aryan Age. Its broader name reflects the expanding and increasingly interconnected scope of India’s energy transition, spanning hydrogen, renewable power, industrial decarbonisation, infrastructure, shipping, mobility, manufacturing, investment and international trade.

Discussions are expected to focus on project bankability and demand creation, infrastructure and technology deployment, domestic manufacturing and supply-chain resilience, and international market access.

Green hydrogen: the headline and the gap

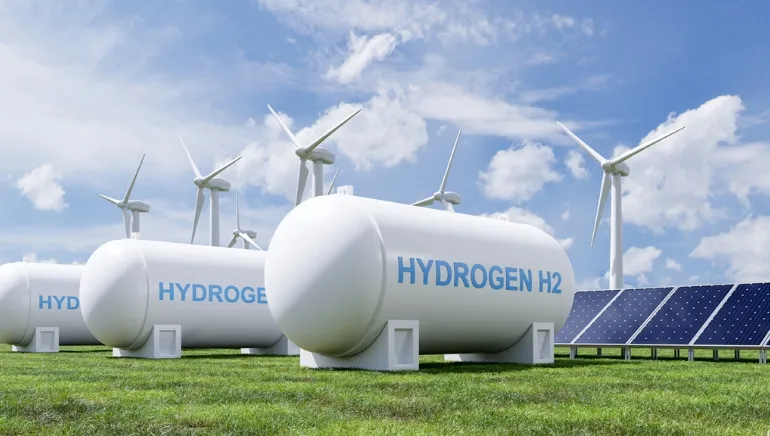
Green hydrogen has been one of the most closely watched elements of India’s energy strategy since the launch of the National Green Hydrogen Mission in 2023. The mission targets 5 million tonnes a year of green hydrogen production capacity by 2030, with the aim of reducing import dependence, decarbonising heavy industry and creating an export industry.

The timing is apt: global energy markets remain volatile, with crude prices hovering around $100 a barrel this week, sharpening the case for domestic clean fuels.

Incentives under the mission now support 862,000 tonnes a year of green hydrogen production capacity and 3,000 MW a year of electrolyser manufacturing capacity, according to figures cited in the event’s preview coverage. But as of February 2026, only about 8,000 tonnes a year of green hydrogen production capacity had actually been commissioned.

That gap — between capacity awarded incentives and capacity actually operating — is likely to frame much of the conversation in New Delhi. It is not unique to India; green hydrogen projects worldwide have faced delays as developers struggle with costs, financing and uncertain demand.

The cost challenge

Cost remains the central obstacle. Green hydrogen — produced by splitting water using electricity from renewable sources — remains significantly more expensive than grey hydrogen made from natural gas.

In India, green hydrogen production costs range from about ₹397 to ₹560 per kilogram, according to industry analysis, compared with roughly ₹150 to ₹200 per kilogram for grey hydrogen. The lowest price discovered through competitive bidding under the Strategic Interventions for Green Hydrogen Transition (SIGHT) programme stands at about ₹397 per kilogram including GST, for supply to Indian Oil Corporation’s refineries.

Renewable electricity accounts for 50% to 70% of green hydrogen production costs, making access to cheap, round-the-clock clean power essential. That links the hydrogen conversation directly to India’s broader progress on solar, wind, storage and transmission.

India’s cost advantage in solar power gives it a structural edge in this race. Solar tariffs discovered in Indian auctions are among the lowest in the world, and pairing low-cost solar with wind and storage to provide more consistent power is central to bringing green hydrogen costs down.

Water availability is another practical consideration. Electrolysis requires large volumes of purified water, and many regions with the best solar resources are also water-stressed, making desalination and water planning part of the project economics.

Bankability and demand
India has incentivised 862,000 tonnes a year of green hydrogen capacity — but had commissioned only about 8,000 tonnes by February 2026.
TIGI Impact Desk

Beyond cost, developers need certainty of demand. Many planned green hydrogen and ammonia projects are waiting for long-term offtake agreements before committing to final investment decisions. Refineries, fertiliser plants, steelmakers and shipping companies are the most likely early users, but many are cautious about committing to higher-cost fuels without clear policy mandates or price support.

Government-backed tenders, such as those for refineries and fertiliser producers, are one way to create that demand. Discussions at Horizons are expected to examine how such mechanisms can be expanded and how private offtake contracts can be structured to make projects bankable for lenders.

image.png

Manufacturing and supply chains

Domestic manufacturing is another priority. India’s electrolyser manufacturing incentives are designed to build a local supply chain for the equipment at the heart of green hydrogen production, reducing reliance on imports and creating industrial jobs.

The broader clean-energy manufacturing story is gaining momentum in adjacent sectors. Solar cell and module manufacturing capacity has expanded rapidly, and battery manufacturing is attracting growing investment — developments that strengthen India’s position as a potential exporter of clean-energy equipment and fuels.

Trade and global markets

International market access is also on the agenda. India has positioned itself as a potential exporter of green hydrogen and its derivatives, such as green ammonia, to markets in Europe and East Asia that are seeking to decarbonise but lack sufficient domestic renewable resources.

Achieving that ambition will require competitive production costs, port and shipping infrastructure, certification frameworks recognised by importing countries and long-term supply agreements. Global trade dynamics — including tariffs, carbon-border mechanisms and geopolitical tensions — will also shape which export markets are accessible.

A reality check, not a retreat

The mood in New Delhi is likely to be pragmatic rather than pessimistic. The gap between incentivised and commissioned capacity reflects the early stage of a complex industry, not necessarily a failure of policy. Large industrial projects take years to develop, and green hydrogen requires coordination across power generation, water supply, electrolysers, storage, transport and end-use industries.

Still, the numbers underline the scale of the challenge. Reaching 5 million tonnes a year by 2030 from about 8,000 tonnes commissioned in early 2026 would require an extraordinary acceleration over the next four years. Policymakers and industry leaders will be under pressure to show that the pipeline of awarded projects can move from paper to production.

Why it matters

For India, green hydrogen is about more than climate targets. It offers a potential route to reduce dependence on imported fossil fuels, decarbonise heavy industries such as steel and fertilisers, and build a new export sector. The country’s abundant solar resources and growing manufacturing base give it genuine advantages in the global race.

Turning those advantages into operating projects will require bankable contracts, lower costs and consistent policy support. Horizons Clean Energy Expansion India 2026 offers a timely forum to assess where India stands — and what must change for its clean-energy ambitions to be realised at the scale and speed that its targets demand.

TagsHorizons Clean Energy IndiaGreen HydrogenNational Green Hydrogen MissionS&P GlobalWorld Hydrogen IndiaClean EnergyElectrolysersSIGHT SchemeEnergy TransitionNew DelhiDecarbonisationRenewable EnergySustainability

Reader reviews

Sign in to rate and review this article.
Loading reviews…