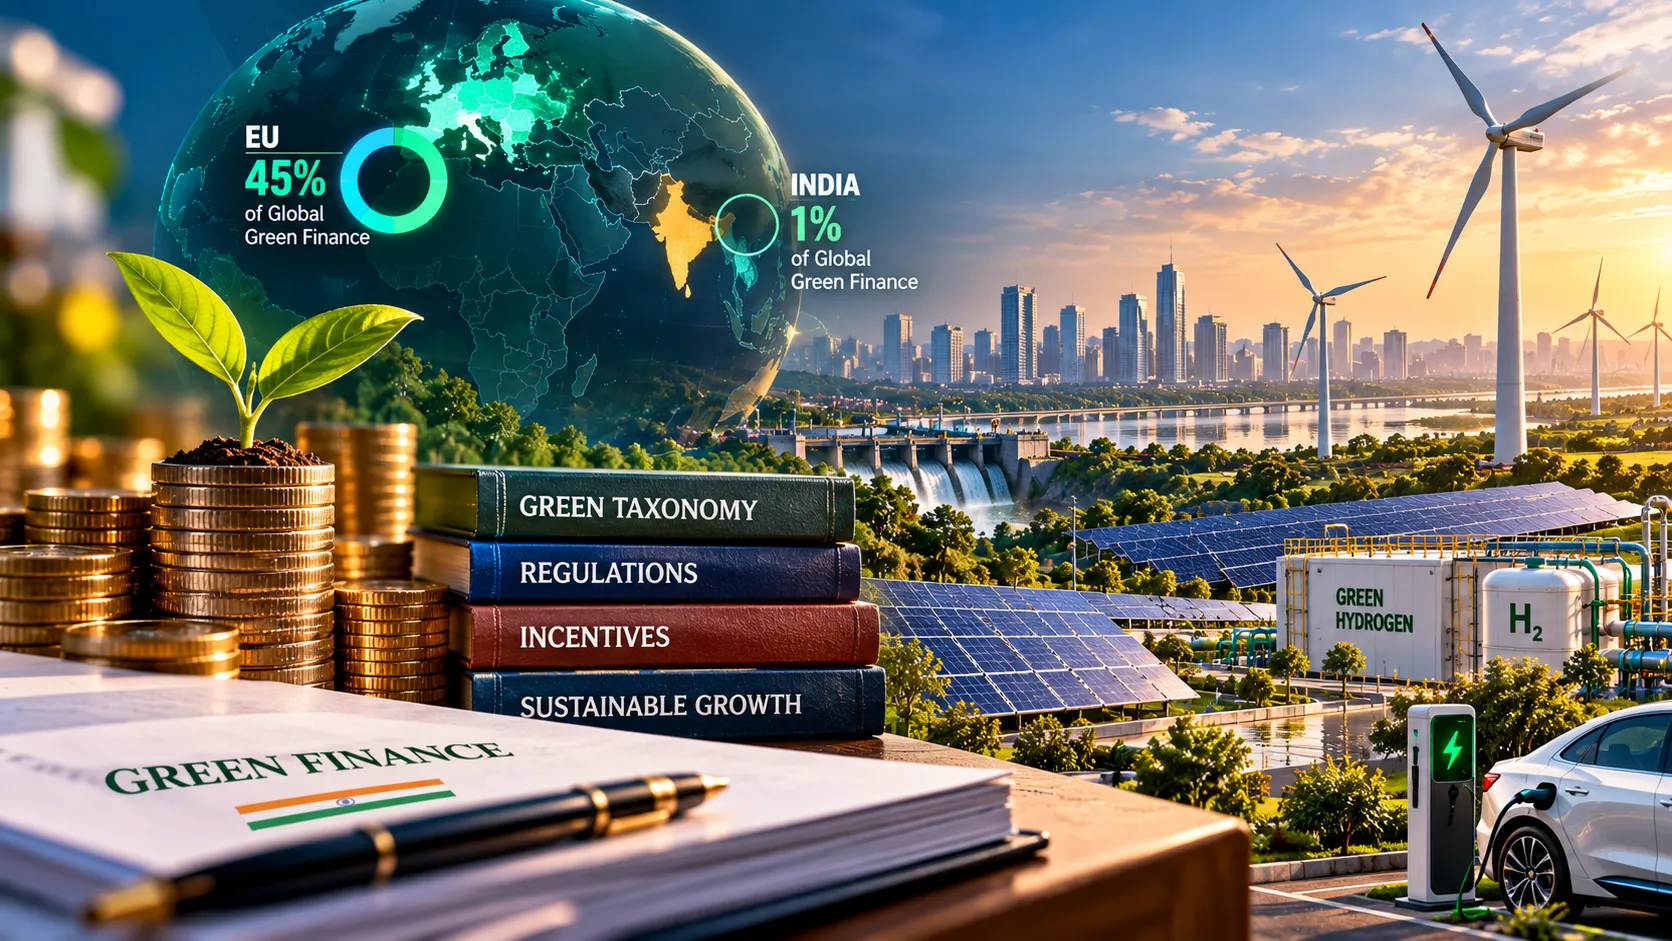
India has some of the world's most ambitious clean energy goals, but it is attracting only a sliver of the global capital flowing into green finance. The country accounts for about 1% of the global green finance market, compared with roughly 45% for the European Union, according to an analysis published by Business Standard on October 18.
The author, Rajesh Narain Gupta, founder and chairman of law firm SNG Partners, argues that the gap is not due to a lack of ambition or projects but to the way India's regulatory framework is designed. Fragmented rules, the absence of a binding definition of what counts as green, and a lack of financial incentives are making it harder and more expensive to channel money into climate-friendly investments.
"A well-intentioned regulatory framework without matching financial rewards is like an engine without fuel," Gupta writes. The column reflects his personal views, but it captures concerns that are widely shared among bankers, investors and issuers working in India's sustainable finance market.
Climate risk is no longer distant
Gupta points to recent extreme weather events, including floods in Nepal in August 2026, as evidence that climate risk is an immediate concern for South Asia rather than a distant threat. India is among the countries most exposed to the physical impacts of climate change, from heatwaves and erratic monsoons to floods and cyclones.
At the same time, India needs enormous investment to meet its targets for renewable energy, electric mobility, green hydrogen and energy efficiency, and to adapt its infrastructure and agriculture to a changing climate. Public money alone cannot meet those needs. Mobilising private capital at scale requires a financial system that recognises, rewards and standardises green investment.
No binding green taxonomy
A central problem, Gupta argues, is that India has no finalised, statutory national green taxonomy, a formal classification system that defines which economic activities qualify as environmentally sustainable. Instead, the market relies on interim lists and guidance.
In contrast, the EU taxonomy provides uniform criteria for identifying sustainable activities across member states. That clarity gives investors confidence that the assets they are buying are genuinely green, reduces the risk of "greenwashing," and allows banks and fund managers to design products and report on them consistently.
Without a common definition, every issuer and lender must make its own judgements, often relying on bespoke legal opinions for each green issue. That increases costs, slows transactions and makes it harder for investors to compare products.
Rules without rewards
Gupta's second major criticism is that India's regulators have imposed requirements without offering corresponding incentives.
The Reserve Bank of India has issued directions on climate finance for banks and non-bank lenders, but they include no prudential concessions, such as lower capital requirements or relaxations of the cash reserve ratio or statutory liquidity ratio for green lending. Current RBI rules also bar banks from offering differential interest rates on green deposits, meaning that such deposits are treated commercially like ordinary term deposits. Savers who want to support green projects therefore receive no financial benefit for doing so, and banks have little reason to promote such products.
Environmental, social and governance (ESG) ratings are not yet a mandatory input into bank credit decisions, so a better rating does not automatically translate into a lower cost of capital for companies.