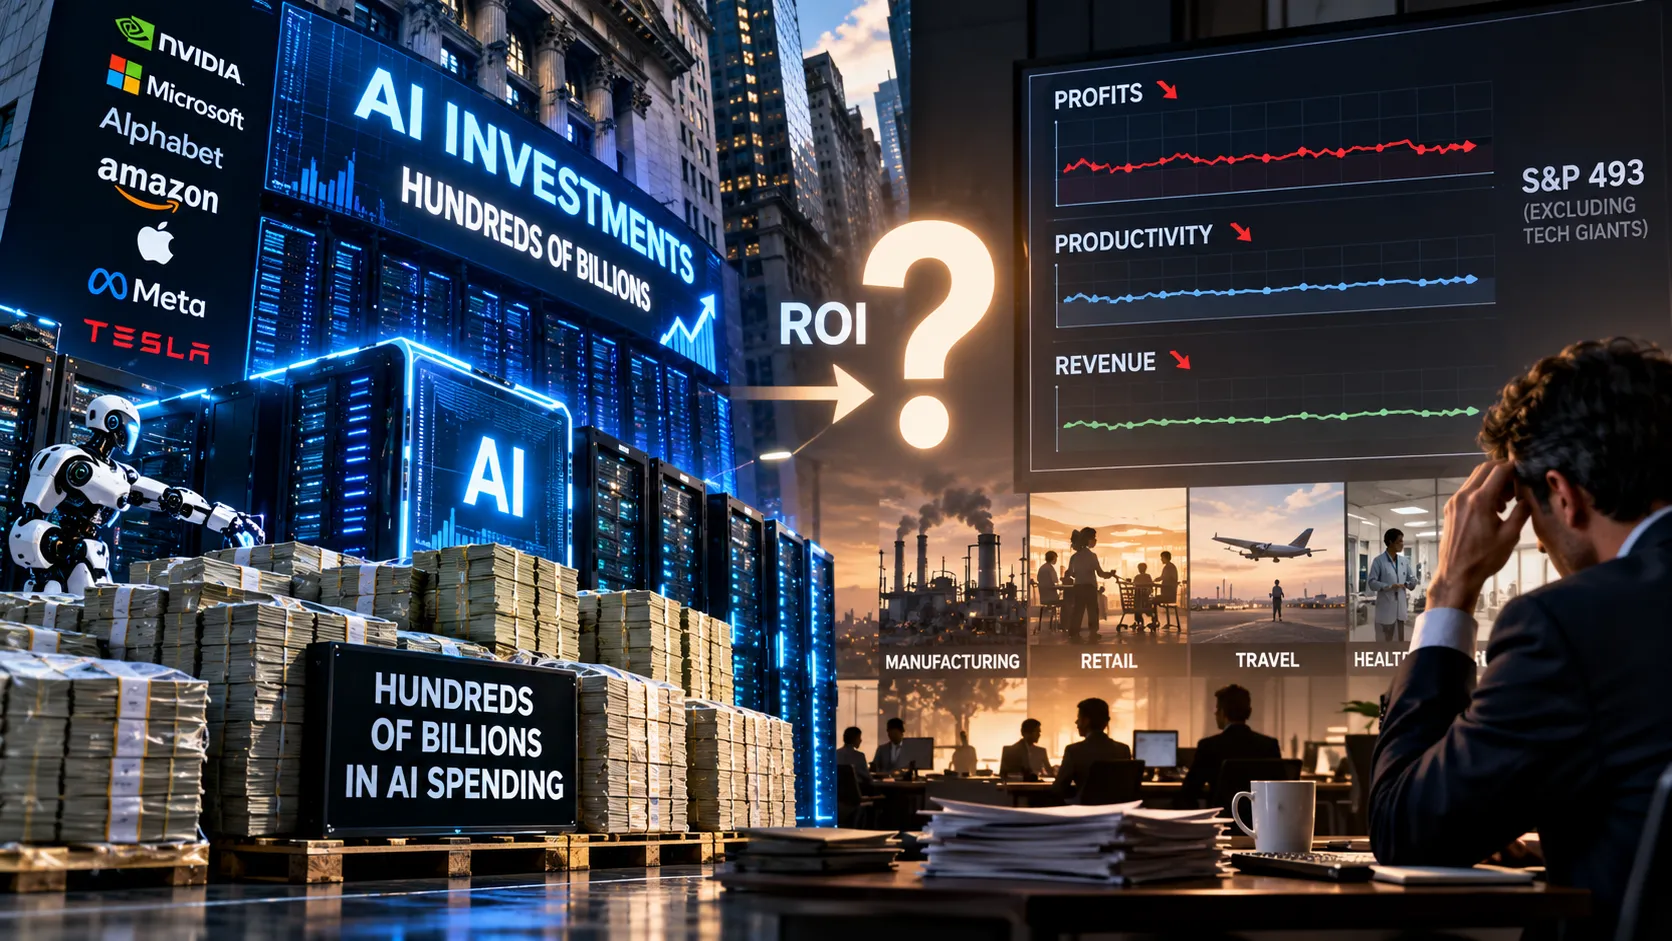
Companies around the world are spending hundreds of billions of dollars on artificial intelligence, but one of Wall Street's most closely followed economists says there is still no sign that the technology is improving the bottom line of most businesses.
Torsten Slok, chief economist at Apollo Global Management, one of the world's largest alternative asset managers, concluded in a recent note that AI has delivered "zero financial payoff to corporate America outside of tech," TechCrunch reported on Sunday, October 25.
Looking beyond the Magnificent Seven
Slok examined what he called the "S&P 493," the companies in the S&P 500 index excluding seven technology giants: Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla. These seven companies, often called the "Magnificent Seven," have driven much of the stock market's gains in recent years, largely because of their role in building and selling AI technology.
By focusing on the other 493 companies, Slok aimed to test whether AI is benefiting the broader economy, not just the companies that make and sell it. He found that profit margins and revenue per worker at these companies appear flat, with no evidence that AI is improving productivity.
Intelligence versus judgment
Slok was sceptical that companies outside technology can turn what he called "increasingly cheap intelligence into higher revenue growth and higher profit margins."
"AI may be a great calculator, but in business, intelligence is mostly judgment," he wrote.
He argued that AI lacks an understanding of accountability, trust, culture and fairness, factors that shape reputational risk and ultimately drive revenue and margins. In other words, the hard parts of running a business are not primarily about processing information, which is what AI does well, but about making decisions in complex human contexts.
A growing body of evidence
Slok's findings add to a growing body of research suggesting that AI has not yet delivered significant productivity gains for most companies. Several studies have found that while AI tools can speed up specific tasks, such as writing code or drafting documents, the gains often fail to translate into measurable improvements in company-wide productivity or profits.
Economists have pointed to several reasons. Companies may need years to reorganise their operations to take full advantage of new technology, as happened with electricity and computers. Employees may use AI for tasks that save time but do not create additional value. And the costs of implementing AI, including software, training and data infrastructure, can offset the benefits.
The productivity paradox, again
The situation echoes the "productivity paradox" of the 1980s and early 1990s, when economist Robert Solow famously observed that "you can see the computer age everywhere but in the productivity statistics." Productivity growth eventually accelerated in the late 1990s, as companies learned to use computers and the internet effectively.
AI optimists argue that a similar pattern will unfold, and that today's investments will pay off as companies redesign workflows and AI capabilities improve. Sceptics counter that the scale of current spending requires returns far sooner and larger than history suggests.
The spending boom
The stakes are enormous. Large technology companies are spending hundreds of billions of dollars a year on data centres, AI chips and energy infrastructure. Those investments are predicated on the assumption that businesses and consumers will eventually pay enough for AI services to justify the cost.
If companies outside technology are not seeing financial benefits, they may become less willing to pay for AI, which could slow revenue growth for AI providers and raise questions about the returns on infrastructure spending.
Market implications
Doubts about AI returns have already rattled markets. South Korea's Kospi, heavily weighted towards memory chip makers that supply AI data centres, has fallen more than 35% from its June peak. Goldman Sachs cited uncertain returns on AI spending among the reasons for cutting its Kospi target.
Apollo itself is a major investor in infrastructure, including data centres, through its private credit and equity businesses. Slok's views are his own analysis rather than a statement of the firm's investment strategy.
What it means for India
Slok's analysis has relevance for India's IT services industry, which is both an adopter and provider of AI. Indian companies such as Infosys are helping clients deploy AI, but they also face pressure as clients demand productivity gains. Infosys cut its revenue growth guidance this week, citing client demands for higher productivity, even as its AI revenue grew 29% sequentially.
If AI fails to deliver financial benefits for clients, demand for AI services could slow. But if AI does improve productivity, it could reduce demand for traditional outsourcing.
The counterargument
Not all economists share Slok's view. Some argue that the benefits of AI are hard to measure in the short term, and that companies are using AI to avoid costs rather than increase revenue, which may not show up in revenue per worker. Others point to specific sectors, such as software development and customer service, where AI has demonstrably improved efficiency.
Measuring productivity is hard
Part of the debate stems from the difficulty of measuring AI's impact. Revenue per worker and profit margins are influenced by many factors, including demand, pricing, wages, interest rates and energy costs, which makes it hard to isolate the effect of a single technology. Companies may also be using AI in ways that improve quality or customer satisfaction without immediately boosting financial metrics.
Economists have proposed various approaches to measure AI's contribution, from studies of specific tasks and occupations to surveys of business adoption and analysis of company-level data. The emerging consensus is that AI can deliver large gains for specific tasks, but that translating those gains into economy-wide productivity growth takes time and organisational change.
What comes next
The debate over AI's economic impact will continue as more data becomes available. Corporate earnings, productivity statistics and surveys of business adoption will offer evidence on whether AI is beginning to deliver.
For investors, Slok's note is a reminder that the AI boom rests on expectations that have yet to be fully validated outside the technology sector, and that the gap between spending and measurable returns will remain a central question for markets in the months ahead. Corporate executives remain broadly optimistic, with many surveys showing that large companies plan to increase AI investment, even if they acknowledge that returns have yet to materialise at scale.