While India's largest IT companies struggle to grow, some mid-sized rivals are expanding rapidly, and Coforge's latest results show how acquisitions are reshaping the competitive landscape.
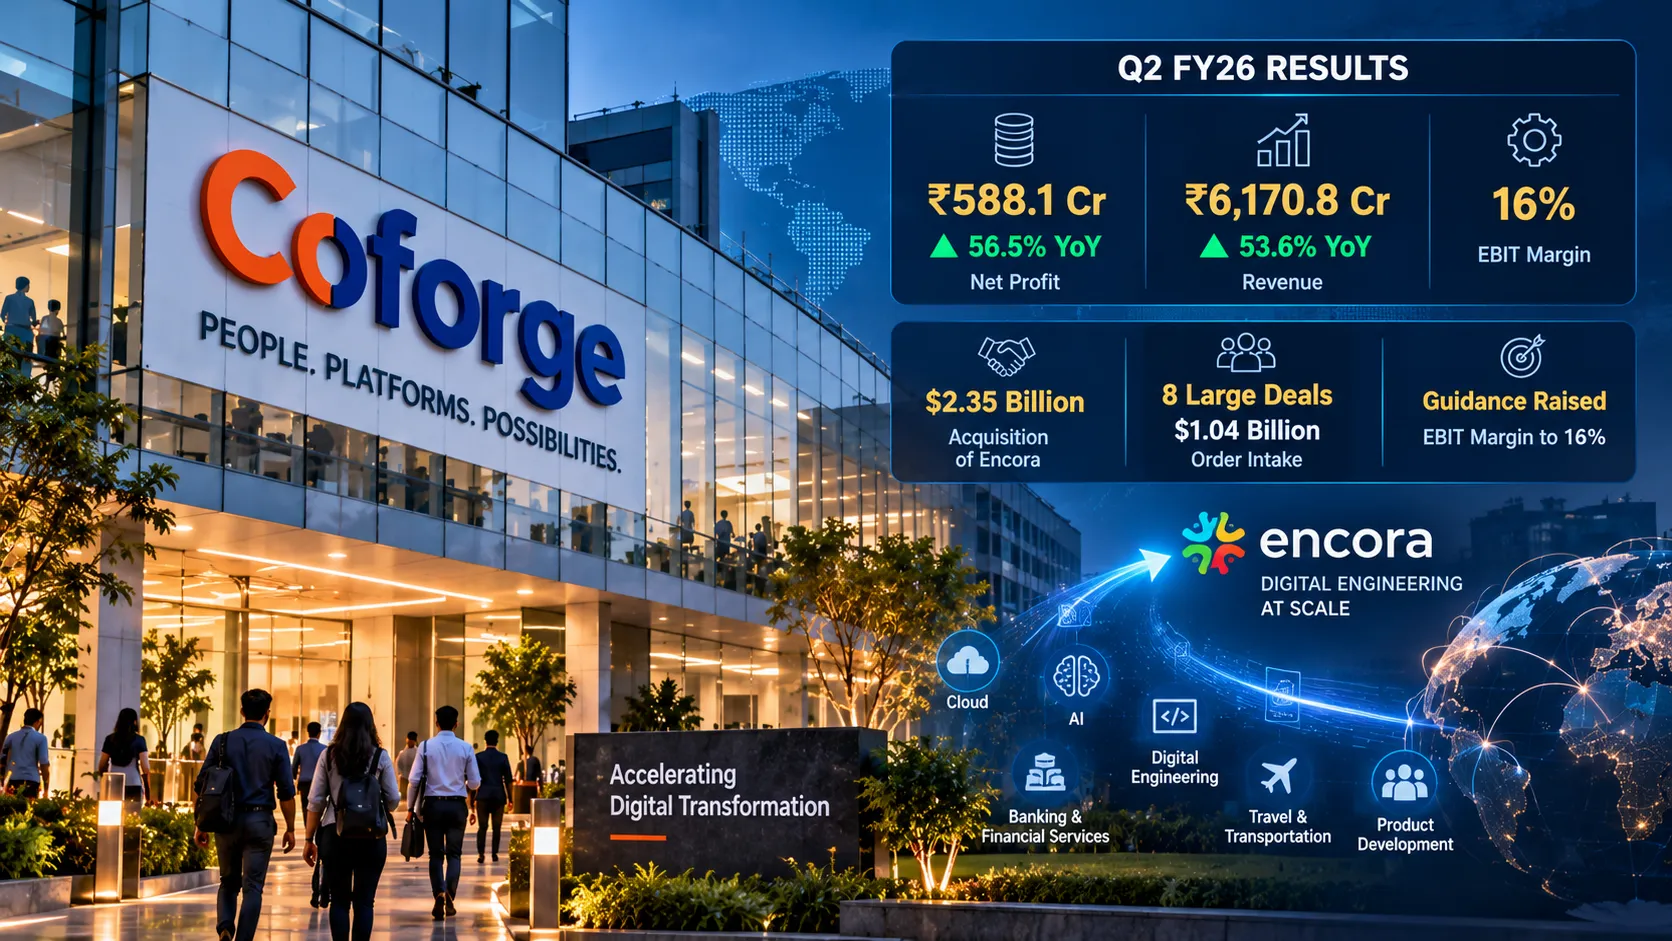
The Noida-based IT services company reported consolidated net profit of ₹588.1 crore for the July-September quarter, the second quarter of its 2026-27 financial year, up 56.5% from ₹375.8 crore a year earlier and 13.4% higher than the previous quarter. Revenue rose 53.6% to ₹6,170.8 crore.
Earnings before interest and tax (EBIT) increased 67.8% to ₹984.7 crore, giving an EBIT margin of 16%.
The strong growth was driven largely by a full quarter of contribution from Encora, the digital engineering company Coforge acquired for $2.35 billion. Zee Business reported that profit and revenue fell short of analyst estimates, which may temper the market's reaction.
Large deals and guidance
Coforge signed eight large deals during the quarter, with total order intake of $1.04 billion. Strong order intake is a key indicator of future revenue growth in the IT services industry.
The company raised its guidance for EBIT margin for the 2026-27 financial year to 16% from 15.5%, according to HDFC Sky. Upstox reported that operating margin guidance moved up to 17% from 15.5-16%. The difference may reflect different margin definitions, and investors will look to the company's own disclosures for clarity.
The Encora acquisition
Encora, which specialises in digital engineering, product development and AI-led software services, adds capabilities and clients that complement Coforge's traditional strengths in banking, insurance and travel. The acquisition significantly expanded Coforge's size, making it one of the larger mid-tier players in India's IT industry.
Acquisitions of this scale carry integration risks, including retaining key employees and clients and combining different corporate cultures. The latest results suggest the integration is progressing, though the shortfall against analyst estimates indicates that the combined business has not yet fully met expectations.
Mid-tier versus large caps
Coforge's growth contrasts sharply with the performance of India's largest IT companies. Infosys, reporting the same week, posted revenue growth of about 10.7% and cut its full-year growth guidance to 1-2% in constant currency, citing pricing pressure and client demands for productivity gains.
Mid-tier companies such as Coforge, Persistent Systems and LTIMindtree have generally grown faster than the largest players in recent years. They are often more agile, focused on specific industries and capabilities, and able to win market share from larger competitors as clients consolidate vendors.
Acquisitions have also allowed some mid-tier companies to accelerate growth and add capabilities in areas such as digital engineering, data and artificial intelligence.
The AI opportunity and threat
Like the rest of the IT industry, Coforge faces both opportunities and threats from artificial intelligence. AI creates demand for new services, such as building AI applications, modernising data infrastructure and integrating AI agents into business processes. But it also reduces demand for some traditional services, as clients use AI to automate work.
Companies that build strong AI and digital engineering capabilities are expected to fare better in this transition. Encora's focus on product engineering and AI-led services positions Coforge to capture some of the new demand.
Market context
IT stocks have been under pressure in Indian markets, with the Nifty IT index falling 1.2% on Monday, October 26, after Infosys's guidance cut. Investors have become more cautious about the sector's growth outlook as AI reshapes demand and clients in the United States and Europe remain careful about spending.
Coforge's strong growth may help it stand out, but the shortfall against estimates and broader sector concerns could limit any rally in its shares.
Client concentration
Coforge has historically derived a significant share of revenue from banking, financial services and insurance clients, as well as from the travel and transportation sector. The Encora acquisition diversifies its client base into technology companies, healthcare and other sectors that are investing in product development.
Diversification can reduce the company's vulnerability to slowdowns in any single industry, an important consideration as high energy prices affect sectors such as travel and airlines.
Talent and execution
Integrating a large acquisition while continuing to grow organically puts heavy demands on management. Retaining Encora's engineers and leaders, many of whom are based in Latin America and the United States, will be important to delivering the expected benefits. Coforge's ability to cross-sell services to the combined client base will also determine how much value the deal creates.
The economics of IT acquisitions
Acquisitions have become a common route to growth for mid-sized Indian IT firms, which use them to enter new markets, add specialised skills and gain clients that would take years to win organically. The price of such deals is usually justified by expected revenue synergies, such as selling the acquirer's services to the target's clients and vice versa, as well as cost savings from using India-based delivery centres.
The risks are significant. Acquired companies may lose key staff after a deal, clients may move work elsewhere during the transition, and integration costs can weigh on margins. Large acquisitions are often financed partly with debt, which increases financial risk if growth slows. Investors therefore watch closely for evidence that acquisitions are delivering the promised benefits, including improvements in margins and the share of revenue coming from cross-selling.
Valuation and expectations
Coforge's shares have historically traded at a premium to many peers, reflecting its strong growth record. That premium leaves less room for disappointment, which helps explain why a miss against analyst estimates can weigh on the stock even when headline growth is strong. Delivering consistently on margin guidance will be important for sustaining investor confidence.
What comes next
Coforge will need to show that it can sustain growth once the acquisition effect is fully reflected in year-on-year comparisons. Organic growth, margin improvement and the conversion of large deal wins into revenue will be key metrics for investors.
The company's performance will also be a test of whether mid-tier IT firms can continue to outpace the industry giants as artificial intelligence transforms demand for technology services. If Coforge can deliver on its expanded margin guidance while integrating Encora, it would strengthen the case for acquisition-led growth in Indian IT. Analysts will also watch for updates on deal pipelines in banking, insurance and travel, sectors that remain central to Coforge's business, as well as the contribution of Encora's product engineering work to new client wins in technology and healthcare.