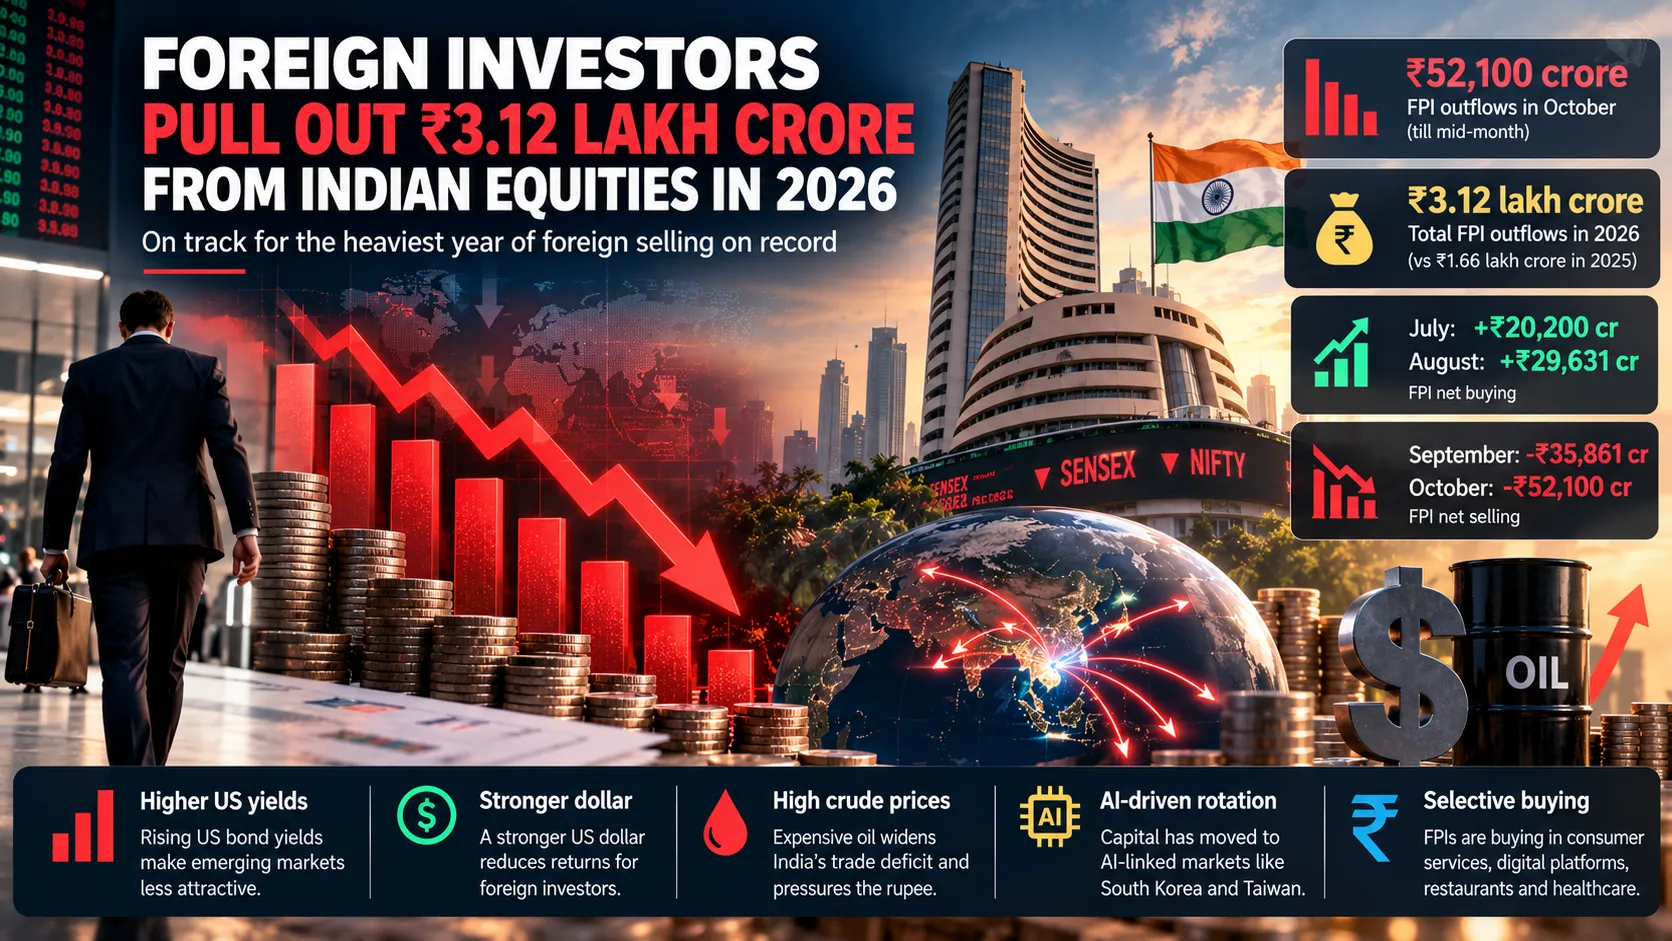
Foreign investors are on track for their heaviest year of selling in Indian equities on record. Foreign portfolio investors (FPIs) withdrew ₹52,100 crore from Indian shares in October up to the middle of the month, according to depository data reported on October 18, taking total net outflows in 2026 to ₹3.12 lakh crore.
That is almost double the ₹1.66 lakh crore that foreign investors pulled out in 2025, which was itself a year of heavy selling. The sustained exodus has weighed on the Sensex and Nifty, weakened the rupee and raised questions about India's attractiveness relative to other emerging markets.
There was a tentative sign of stabilisation late last week: FPIs turned marginal net buyers on October 16. But analysts cautioned that a single session of buying does not yet signal a sustained change in direction.
A volatile year for foreign flows
Foreign flows have swung sharply in recent months. FPIs were net buyers of Indian equities in July, investing ₹20,200 crore, and again in August, with net purchases of ₹29,631 crore. That brief recovery reversed in September, when they withdrew ₹35,861 crore, and the selling has accelerated in October.
The scale of the outflows stands out because India's domestic investors have continued to buy. Systematic investment plans in mutual funds, insurance companies and pension funds have provided steady support for the market, absorbing much of the foreign selling. Equity mutual fund inflows rose 5% year on year to ₹1.83 lakh crore in the first half of the current financial year, according to industry data.
That domestic cushion has prevented a collapse in Indian share prices, but it has not been enough to keep the market rising. Indian equities have underperformed many global peers in 2026.
Why foreign investors are selling
Analysts point to a combination of global and local factors. Dheeraj Gaur, chief investment strategy officer at Choice Wealth, said higher US bond yields, a stronger US dollar and expensive crude oil are pushing foreign investors away from Indian markets.
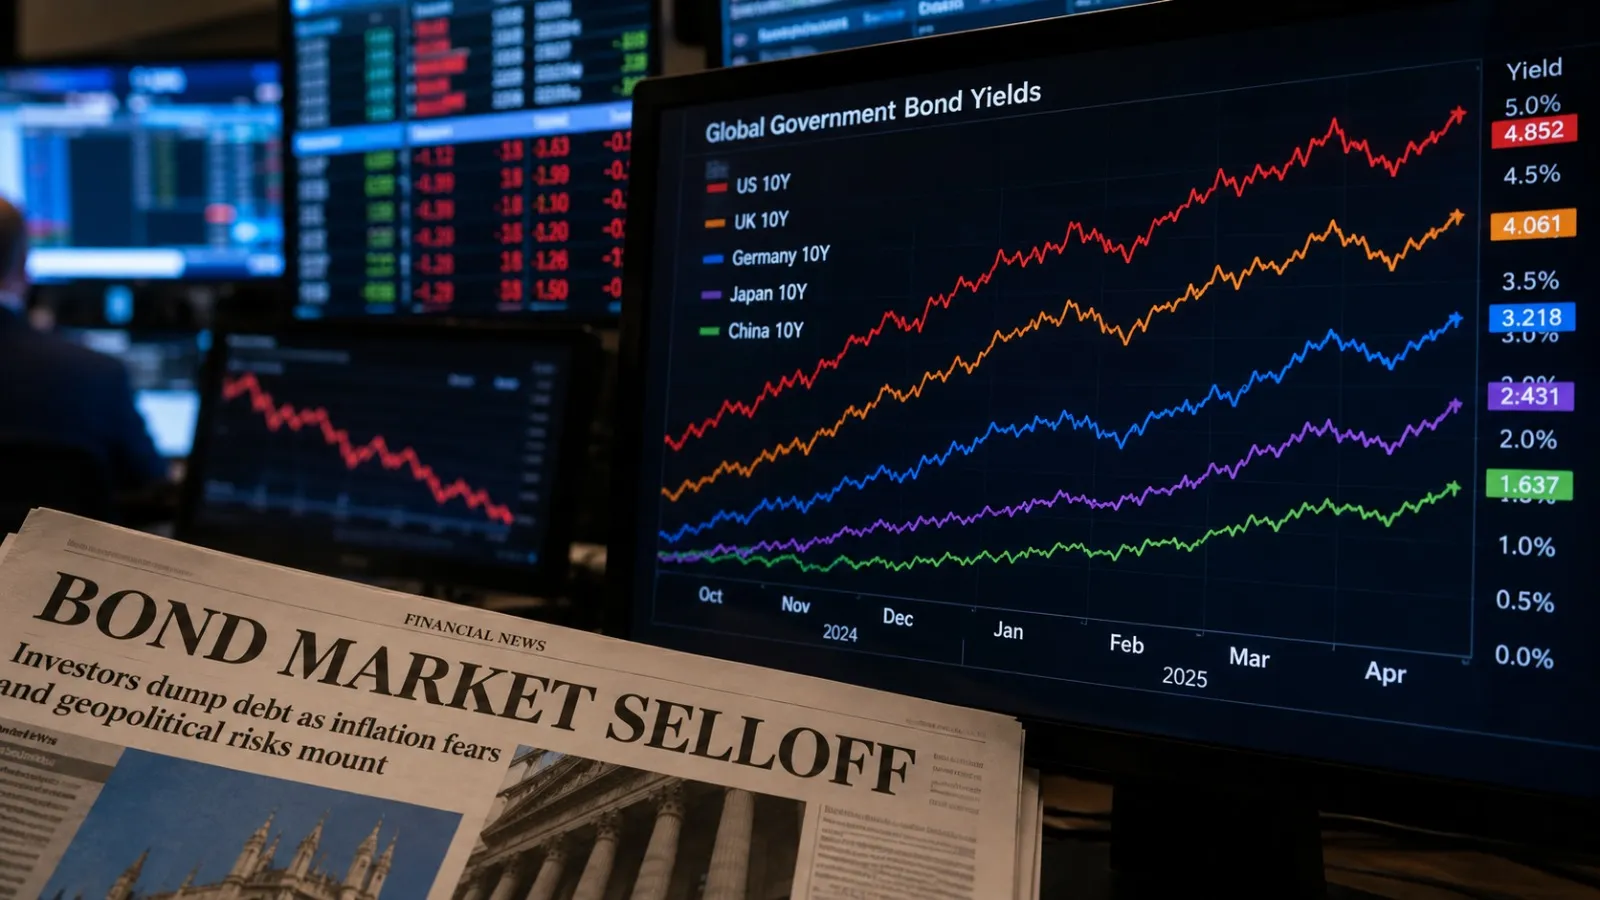
Rising US yields are perhaps the most important driver. When safe US government bonds offer high returns, the relative appeal of riskier emerging market assets falls. US inflation rose to 3.7% in September, keeping expectations alive that the Federal Reserve could raise interest rates further. The 10-year US Treasury yield climbed above 5.3% earlier this year, levels not seen in decades.
A strong dollar compounds the problem. For a foreign investor, gains in Indian shares can be wiped out if the rupee weakens. The rupee has traded near record lows against the dollar in 2026, recently around 94 to 95 per dollar.
Oil is the third pressure point. India imports most of its crude oil, so higher prices widen its trade deficit, weaken the currency and squeeze corporate margins. Brent crude has traded well above $100 a barrel for much of the year amid conflict in the Middle East and disruptions around the Strait of Hormuz.
Finally, the artificial intelligence boom has redirected capital. Markets such as South Korea and Taiwan, home to major chipmakers including SK hynix, Samsung Electronics and TSMC, attracted large foreign inflows earlier in the year as investors chased exposure to AI hardware. India, which has fewer listed companies directly tied to AI infrastructure, lost out in that rotation.
Which sectors are being sold and bought
The selling has not been uniform. According to market data, foreign investors have been net sellers of financial services and oil-related stocks, two of the heaviest sectors in Indian benchmarks. Banks have faced concerns about margins and deposit costs, while oil companies have been hit by high crude prices and regulatory pressure on fuel pricing.
At the same time, FPIs have bought into consumer services, digital platforms, entertainment, restaurants and healthcare services. That pattern suggests foreign investors remain interested in India's long-term consumption story, even as they reduce exposure to the broader market.
Reasons for cautious optimism
V K Vijayakumar, chief investment strategist at Geojit Investments, said the recent shift to buying was supported by a fall in the US 10-year yield from above 5.3% to about 5.08%, along with a stronger rupee. If yields continue to ease, emerging markets including India could regain some appeal.
Pabitro Mukherjee of Bajaj Broking said slower foreign selling points to improving sentiment, but warned that high crude prices remain a concern. The weekend decision by US President Donald Trump to waive sanctions on Russian energy exports has eased oil prices slightly, but the situation in the Gulf remains volatile.
Valuations may also help. After a long period of underperformance, Indian shares are cheaper relative to their own history than they were in 2024, which could attract investors looking for long-term opportunities. India's economy continues to grow faster than most major economies, and the International Monetary Fund recently raised its forecast for India's growth this year.
The rupee and the RBI
The outflows have added pressure on the rupee, which has traded near record lows against the dollar in 2026. The Reserve Bank of India has intervened in the currency market to smooth volatility, drawing on its foreign exchange reserves. Economists have also cut their estimates for India's balance-of-payments surplus for the current financial year, citing higher energy costs, West Asia tensions and weaker foreign investment flows.
A weaker currency can help exporters, but it raises the cost of imports, particularly oil, and can feed into inflation. India's retail inflation rose to 5.54% in September from 4.83% in August, with food inflation at 7.74%, leaving the RBI balancing support for growth against the need to keep prices in check.
What to watch
Analysts say three factors will determine whether foreign selling eases: the direction of Brent crude prices, the state of US-Iran relations and the strength of September-quarter corporate earnings now being reported by Indian companies.
The Federal Reserve's next policy meeting on October 27 and 28 will also be closely watched. Markets currently expect the Fed to hold rates, but any signal of further tightening could push US yields higher and renew pressure on emerging markets.
The Jio Platforms initial public offering, which opens on October 21 and is India's largest ever, will be another test of foreign appetite for Indian assets. Strong demand from global investors would be a welcome sign for a market that has spent much of 2026 watching foreign money head for the exit.
For now, India's equity market is in an unusual position: supported by record domestic savings flows, but held back by the steady retreat of foreign capital. Until global yields, the dollar and oil prices move in India's favour, that tug of war is likely to continue.