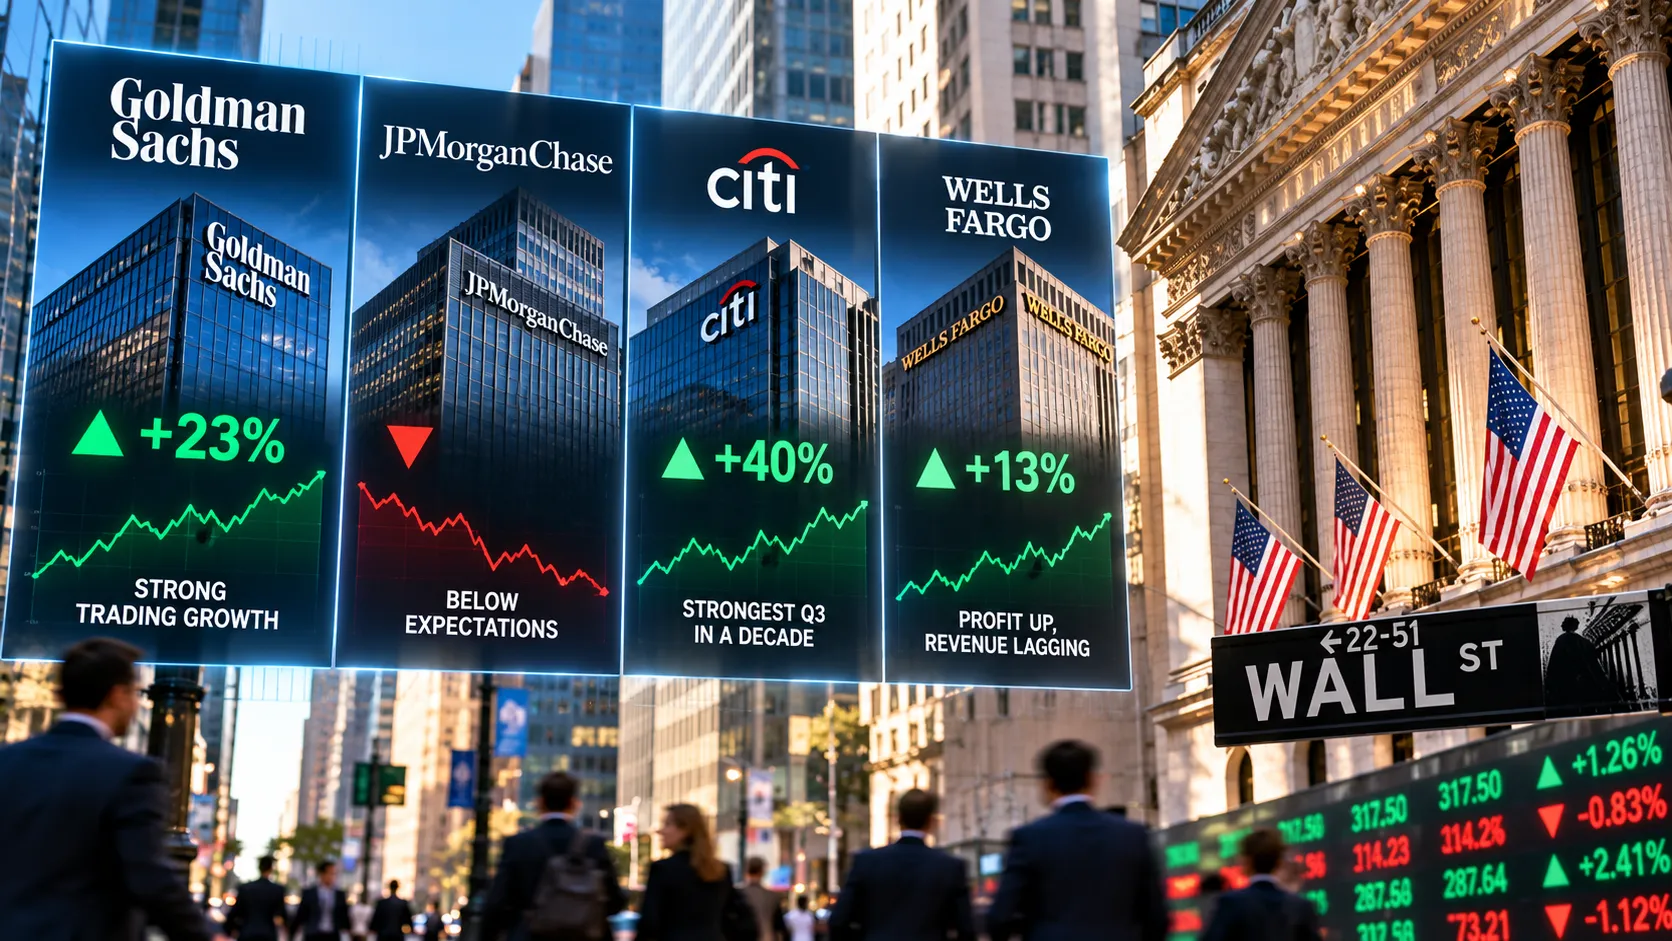
Wall Street's biggest banks opened the third-quarter earnings season on October 13 with results that pointed in strikingly different directions. A trading boom lifted Goldman Sachs to a blowout quarter, Citigroup delivered its strongest third-quarter revenue in a decade, and JPMorgan Chase, usually the most dependable of the group, fell short of analysts' expectations.
The results offered investors an early read on the health of the US economy, corporate dealmaking and the impact of rising interest rates. On balance, they suggested that capital-markets businesses are thriving, while the traditional engines of banking face a more complicated environment.
Goldman's equities machine
Goldman Sachs reported net revenues of $18.68 billion for the quarter ended September 30, up 23% from a year earlier. Net earnings reached $5.29 billion, or $17.01 per diluted share, far above the roughly $13 a share analysts had forecast and up from $12.25 a year earlier. Its annualised return on equity was 18.7%.
The star performer was equities trading. Revenue from that business surged 72% to $6.44 billion, driven by strong client activity and prime brokerage, where Goldman lends to and services hedge funds. Its Global Banking & Markets division, which houses trading and investment banking, posted revenues of $13.46 billion, up 32%. Investment banking fees rose 21% to $3.22 billion, while fixed income, currencies and commodities revenue was broadly flat at $3.47 billion.
The asset and wealth management division grew revenues 14% to $5.05 billion, and assets under supervision climbed to $4.10 trillion, helped by $83 billion of net inflows. The one weak spot was Platform Solutions, the remnant of Goldman's consumer push. Its revenue fell 72% to $170 million, mainly because of markdowns on the Apple Card loan portfolio.
Goldman returned $4.49 billion to shareholders in the quarter, including $3 billion of share buybacks, and declared a quarterly dividend of $5.00 per share. Its shares rose almost 4% in early trading, leading bank stocks higher.
JPMorgan's rare stumble
JPMorgan, the largest US bank by assets, reported earnings of $5.57 per share, short of the roughly $5.90 analysts had expected. Excluding $658 million of losses on securities, earnings were $5.75 a share. Net revenue rose 8% to $50.2 billion, also below forecasts, and net income climbed 6% to $15.3 billion.
The shortfall reflected weaker-than-expected fixed-income trading and expenses that grew faster than revenue. Total trading revenue rose 15% from a year earlier to $10.3 billion but slipped from the previous quarter and came in slightly below expectations. Investment banking fees rose 14% year on year but fell 8% from the second quarter.
There were bright spots. Net interest income, the difference between what the bank earns on loans and pays on deposits, rose 13% to about $27 billion, and JPMorgan raised its full-year net interest income guidance to $106.2 billion, a sign that higher rates continue to support the core lending business.
Chairman and chief executive Jamie Dimon struck a characteristically cautious tone. He said the US economy remains strong, supported by business investment and steady consumer spending, but warned that "large fiscal deficits, sticky inflation, elevated asset prices, rising interest rates and geopolitical conditions" continue to shift under the surface. Those forces may prove manageable, he said, but the bank remains prepared for a wide range of outcomes.