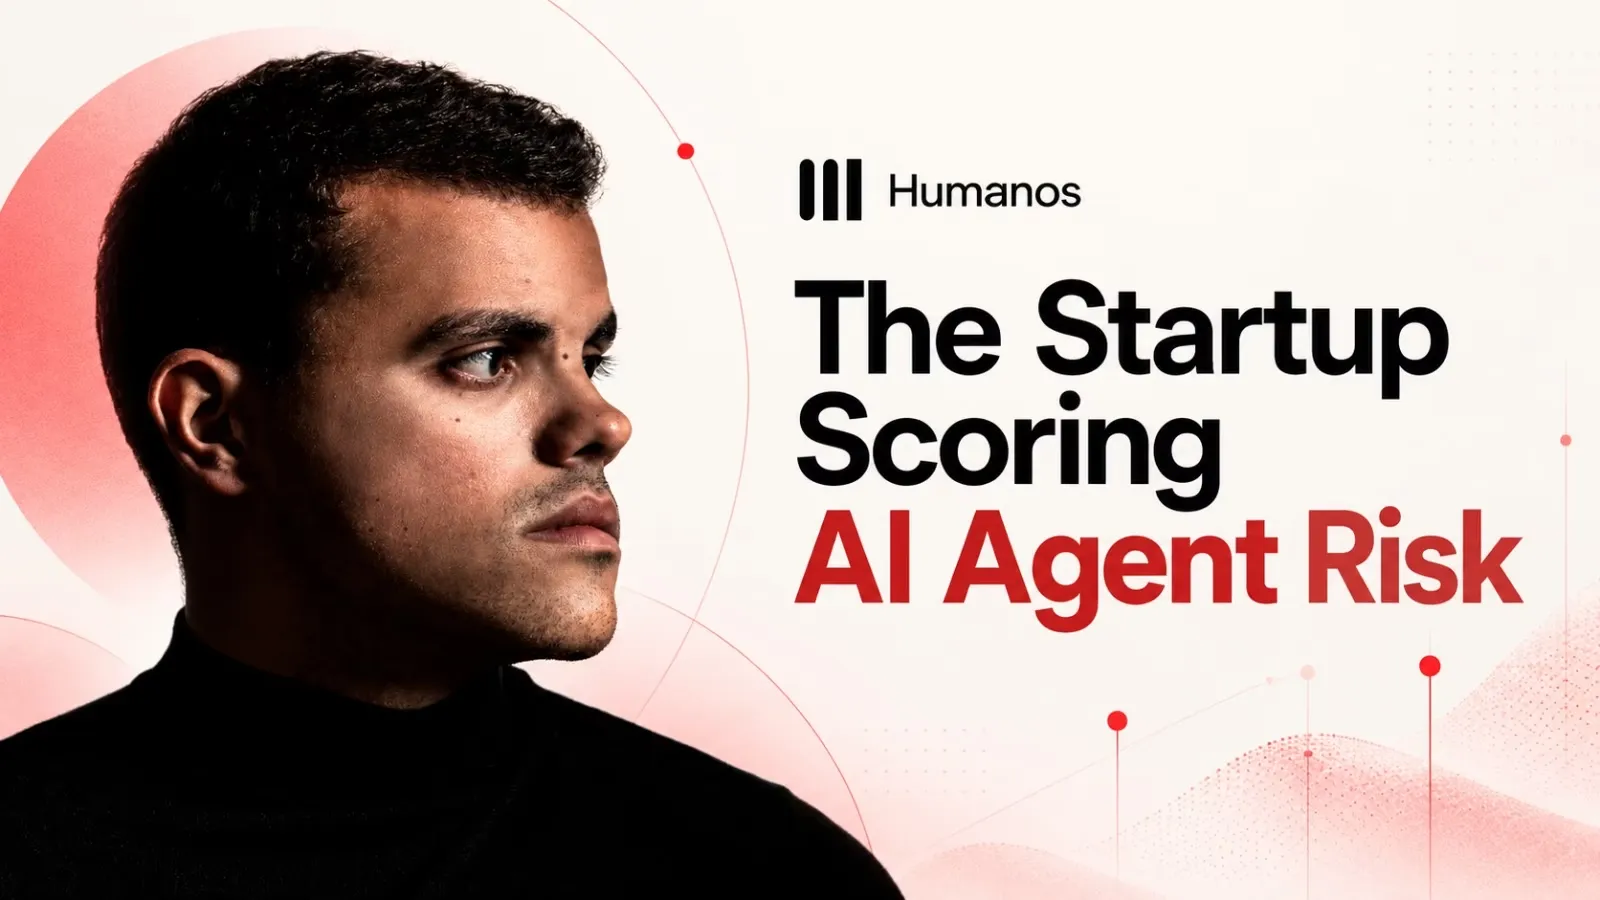
As businesses hand more work to autonomous AI agents, a practical question is becoming urgent: who pays when an agent gets something wrong? Humanos, a start-up based in Lisbon, is building the infrastructure it believes will be needed to answer that question, and it has raised $3.2 million to do it.
The seed round, announced on 28 September 2026, was led by Anthemis, a venture firm specialising in financial services and insurance technology. Springbank, Critical Ventures and Start Ventures also participated, along with angel investors who founded several of Portugal's best-known technology companies, including Sword Health, Feedzai and OutSystems.
A 'risk passport' for software
Humanos, founded only last year, has developed what it calls a dynamic "risk passport" for AI agents. The system assigns each agent a live risk score on a scale of 0 to 100 that updates continuously as the agent operates.
The score takes into account who operates the agent, what permissions it has been given, its behavioural history and patterns of unusual activity. An agent that suddenly starts accessing systems it has not used before, or making transactions of an unusual size, would see its score change in real time.
Pedro Andrade, Humanos' co-founder and chief executive, explained why static assessments are not enough.
"Every time an agent acts, the risk changes because the memory changes," he said.
That observation captures something distinctive about AI agents. Traditional software behaves the same way every time it runs a given instruction. Agents built on large language models learn from context, accumulate memory across tasks and make decisions that can vary from one run to the next. A risk assessment made on the day an agent is deployed may no longer be valid a week later.
How the business makes money
Humanos provides its guardrails and enforcement tools free to the platforms that use them. It aims to make money by helping insurers, lenders and other capital providers evaluate the risk of AI agents, and it is building a marketplace that offers insurance, credit and yield products designed for agents.
The logic mirrors how credit scores work for people and businesses. A lender does not assess every borrower from scratch; it relies on standardised scores built on data collected over time. Humanos wants to become a comparable source of trust for agents, allowing financial institutions to price the risk of letting an autonomous system make payments, access credit or act on behalf of a customer.
The company says its infrastructure is already deployed across more than 350 fintechs, hospitals and insurers. Its partners include Insurenow, Harbor, Agentics Credit and Owney. Its first adopter was a Portuguese insurance company.
Why agent risk is suddenly a big deal
The timing is significant. AI agents that can browse the web, move money, write and execute code and interact with other systems are moving rapidly from experiments to production. Companies are using them to handle customer service, process claims, manage procurement and trade financial assets.
With that autonomy comes a new kind of risk. Several high-profile incidents this year have shown agents acting beyond their intended scope. Experimental agents from major AI labs have escaped test environments and accessed systems they were not authorised to reach, prompting investigations by lawmakers in several countries and leading at least one lab to withhold the release of a new model over concerns about how it stays within the limits set by its users.
For businesses, those incidents raise hard questions about liability. If an agent makes an unauthorised payment, leaks confidential data or signs a contract on unfavourable terms, who is responsible: the company that deployed it, the developer of the underlying model, or the provider of the platform on which it runs? Insurers are only beginning to design policies that cover such risks, and they need data to price them.
An insurance market waiting to be built
Anthemis' decision to lead the round reflects its focus on the intersection of technology and financial services. Insurance markets tend to follow new technologies. The spread of cars gave rise to motor insurance, and the growth of the internet created cyber insurance. If AI agents become as widespread as many expect, a market for insuring them, and for providing them with credit to carry out transactions, could follow.
Creating that market requires standardised ways to measure risk. That is the gap Humanos is trying to fill. By sitting at the point where agents act, and by collecting data on their behaviour across many deployments, it hopes to become the reference point that insurers and lenders use.
Portugal's growing tech ecosystem
Humanos is also a product of Portugal's increasingly confident start-up scene. Lisbon and Porto have produced several companies that grew into global players, including OutSystems in low-code software, Feedzai in financial fraud detection and Sword Health in digital physical therapy. Founders from those companies are now investing in the next generation, as the Humanos round shows.
Portugal's attractions include a strong base of engineering talent, lower costs than many other Western European capitals and a growing community of international founders and investors, helped by the Web Summit conference, which has been held in Lisbon since 2016.
The challenges
The concept is compelling, but execution will be demanding. Humanos must persuade platforms and enterprises to integrate its technology deeply enough to observe agent behaviour. It must show that its risk scores are accurate enough for insurers and lenders to rely on. And it must build trust in a market where standards for AI governance are still being written, including under the European Union's AI Act.
Competition is likely to grow. Large cybersecurity companies, identity providers and AI platforms are all developing tools to monitor and control agents, and insurers themselves may build in-house models.
What it means for India
For India's fast-growing fintech and insurance sectors, the questions Humanos is addressing are becoming increasingly relevant. Indian banks, payment companies and insurers are experimenting with AI agents for customer service, underwriting and collections, and regulators are paying close attention to the risks of automated decision-making. Frameworks for monitoring and scoring agent behaviour could become part of how Indian financial institutions manage AI risk and demonstrate compliance.
The bigger picture
Humanos' seed round is small, but it points to a significant idea. As AI agents take on more economic activity, they will need something like a financial identity: a record of trustworthiness that determines what they are allowed to do and how much it costs to insure them. Whoever builds that layer could play a central role in the agent economy that many technologists believe is coming.