India is positioning artificial intelligence as its next major financial sector growth driver following the transformative success of the Unified Payments Interface, with policymakers, banks and fintech companies increasingly exploring autonomous AI agents for applications spanning credit assessment, fraud detection and personalised banking services across the country's financial networks. The ambition reflects a deliberate attempt to replicate, in the AI domain, the kind of infrastructure-led transformation that UPI achieved for digital payments, where India built a low-cost, interoperable public payments rail that fundamentally reshaped how the country's population transacts, with the goal of achieving a similarly transformative and internationally influential position in AI-driven financial services.
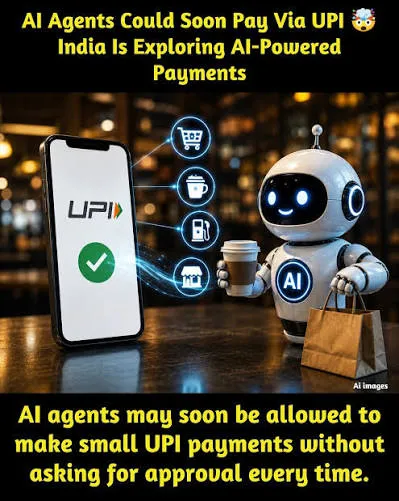
The specific use cases being explored span several distinct categories of financial services application. Autonomous credit assessment agents, capable of evaluating loan applications using a considerably broader and more dynamic set of data signals than traditional rules-based underwriting systems, represent one of the more commercially advanced applications currently under development, building on India's existing strength in alternative-data-driven lending that has emerged over recent years to serve population segments underserved by conventional credit-scoring approaches. Fraud detection represents a second major application area, where AI agents capable of monitoring transaction patterns in real time across India's enormous digital payments volume offer the potential to identify and prevent fraudulent activity at a speed and scale that manual or purely rules-based fraud monitoring systems cannot match. Personalised banking services represent a third significant application category, encompassing AI agents capable of proactively managing aspects of a customer's financial life — from automated savings optimisation to personalised product recommendations and even autonomous execution of routine financial transactions on a customer's behalf within pre-authorised parameters — a vision of AI-native banking that extends considerably beyond the chatbot-based customer service applications that have represented the more common near-term AI application within financial services globally to date.
India's push to establish AI leadership within financial services builds directly on the infrastructure and trust foundation that UPI has established over the preceding decade, including the digital identity verification infrastructure, widespread digital payments adoption and regulatory frameworks that UPI's success has helped build across India's population and financial institutions. Policymakers and industry participants pursuing this AI financial services agenda argue that this existing infrastructure gives India a meaningful head start relative to countries attempting to build AI-driven financial services capabilities without a comparably mature underlying digital payments and identity infrastructure already in place. The Reserve Bank of India's approach to regulating AI applications within financial services will play a decisive role in determining how quickly and in what form autonomous AI agents can be deployed across India's banking and lending sector, given the regulator's demonstrated focus on explainability, fairness and systemic risk considerations when evaluating algorithmic decision-making systems within financial services more broadly. Industry participants have generally welcomed the regulator's engagement with AI applications as a necessary and constructive element of building sustainable AI-driven financial services, even as some have cautioned that overly conservative regulatory approaches could slow India's ability to translate its AI ambitions into the kind of rapid, transformative deployment that characterised UPI's own growth trajectory.
For India's fintech sector specifically, the government's explicit framing of AI as the next major financial services growth driver following UPI provides a clear strategic signal that is likely to influence venture capital allocation, corporate research and development investment, and talent flows toward AI-native financial services startups over the coming several years, extending a pattern already visible in recent funding activity across Indian AI-fintech startups building underwriting, fraud detection and personalisation capabilities. Established Indian banks and financial institutions have similarly begun accelerating their own internal AI capability development, recognising that fintech startups building AI-native financial products from the ground up may otherwise capture disproportionate market share in the AI-driven services layer that increasingly appears set to define competitive differentiation within Indian financial services over the coming decade. As India works to translate this strategic AI ambition into concrete deployed capability across its financial sector, the ultimate measure of success will be whether autonomous AI agents can achieve adoption and trust at a scale genuinely comparable to what UPI achieved for digital payments, a considerably higher bar than simply building technically impressive AI capabilities, given how directly UPI's success depended not just on the underlying technology but on the trust, interoperability and near-universal accessibility that made the payments rail genuinely transformative for hundreds of millions of Indian users across income levels and geographic locations. Several Indian banks have already begun piloting limited AI agent deployments within specific, narrowly bounded use cases such as automated loan document processing and preliminary fraud flagging, a cautious, incremental deployment approach that reflects both regulatory prudence and the practical reality that fully autonomous AI agents making unsupervised financial decisions at scale remain a considerably more distant goal than the current generation of AI-assisted, human-supervised decision support tools that most Indian financial institutions have actually deployed to date. International comparisons offer a mixed picture of how quickly other major economies are pursuing similarly ambitious AI-in-finance agendas, with some markets moving more cautiously given stricter data privacy and algorithmic accountability regulatory frameworks, while others have pursued more permissive innovation sandboxes explicitly designed to accelerate experimentation with autonomous financial AI agents, positioning India's specific regulatory approach, still evolving under the Reserve Bank of India's oversight, as an important variable that will likely determine whether the country's AI-in-finance ambitions can achieve the kind of rapid scaled deployment that characterised UPI's own growth trajectory a decade earlier. The Reserve Bank of India has separately indicated it is developing specific supervisory guidance for AI agent deployment within regulated financial institutions, a framework industry participants expect will clarify permissible autonomy levels for AI-driven decisions well before widescale autonomous agent deployment becomes standard practice across Indian banks. Industry observers note that India's fintech sector has historically demonstrated an ability to compress technology adoption timelines considerably faster than comparable markets internationally, a track record that gives some credibility to the government's ambitious AI-in-finance timeline even as the specific technical and regulatory challenges of autonomous financial decision-making remain considerably more complex than the payments infrastructure problem UPI originally solved.