StartupsTrending6 MIN READ

Kuku FM Parent Turns Profitable as Revenue Jumps Sixfold to ₹1,484 Crore Ahead of Planned IPO

Kuku Technologies swung to a ₹182.7 crore profit in FY26 as subscription revenue from its audio and microdrama apps surged, but marketing absorbed more than three-quarters of its costs.

By Shaym Kumar · Author5 October 2026New
Kuku FM Parent Turns Profitable as Revenue Jumps Sixfold to ₹1,484 Crore Ahead of Planned IPO

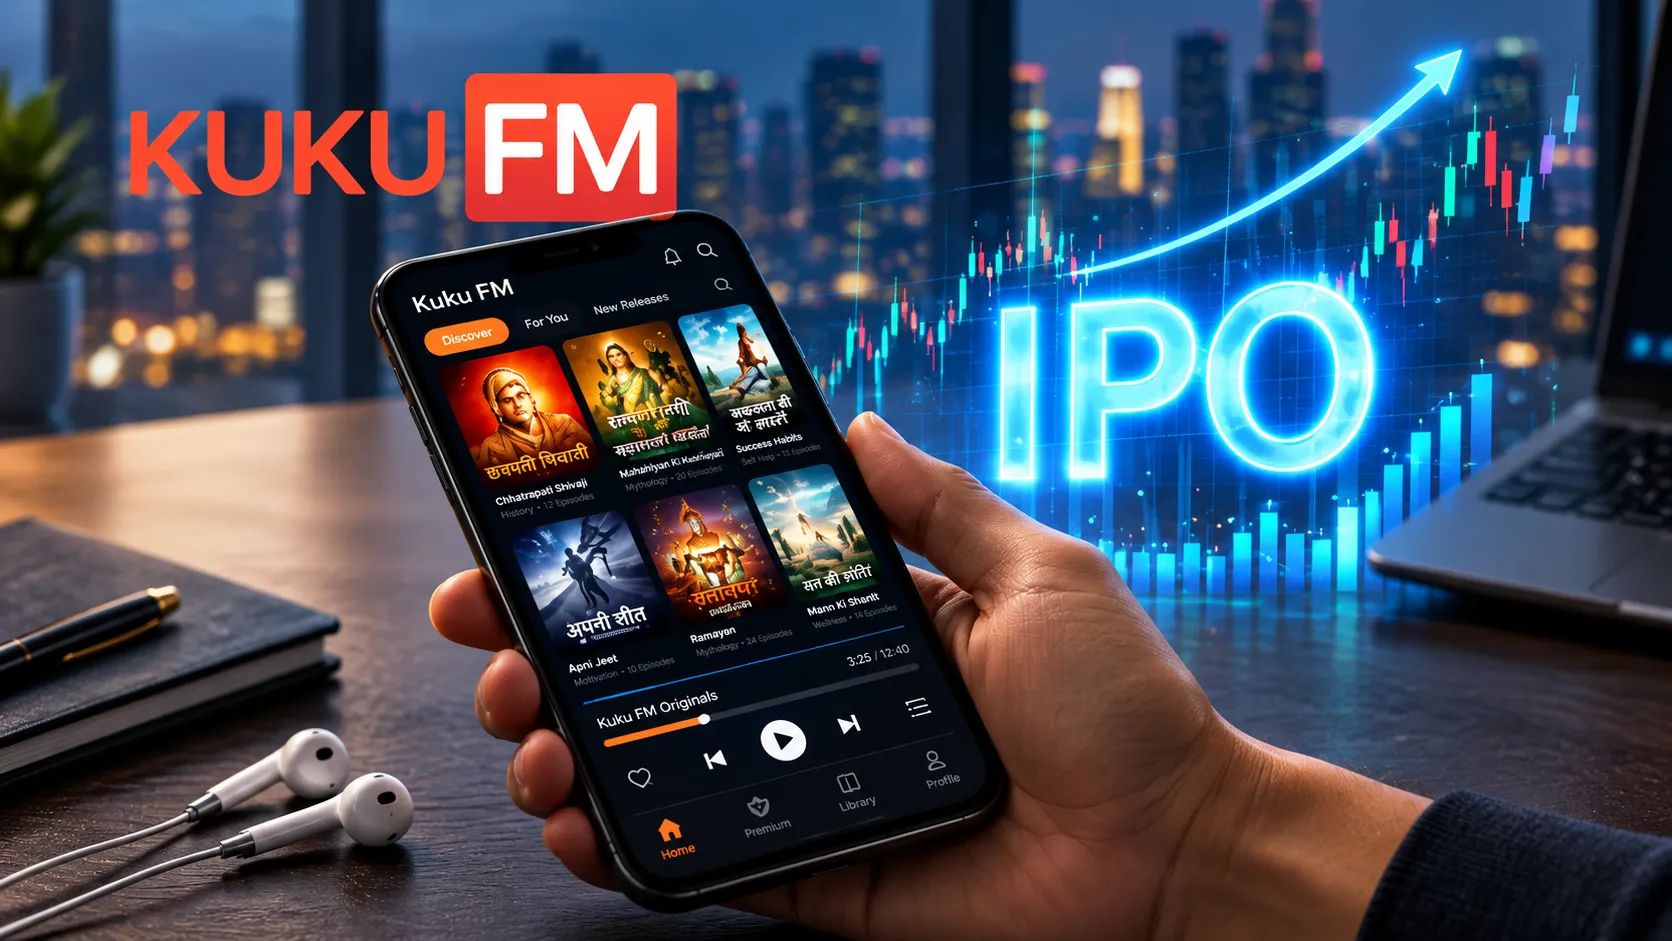
Kuku Technologies, the company behind audio streaming app Kuku FM and microdrama platform Kuku TV, swung to a profit in the financial year ended March 2026 as revenue rose more than sixfold. The results give one of India's most closely watched consumer internet IPO candidates a strong set of numbers to take to public investors.

According to the company's financial statements for FY26, reported by Inc42 and Entrackr, operating revenue rose to ₹1,484.2 crore from ₹241.6 crore a year earlier. The company posted a net profit of ₹182.7 crore, compared with a loss of ₹152.6 crore in FY25. Profit before tax was ₹88.6 crore, and EBITDA swung to a profit of ₹82.9 crore from a loss of ₹159.8 crore.

Including other income of ₹26.2 crore, total income for the year was about ₹1,510.4 crore.

A subscription machine

Almost all of Kuku's revenue comes from subscriptions. Subscription income was ₹1,475.4 crore, more than 99% of operating revenue. Pay-per-view content contributed ₹6.9 crore and advertising just ₹1.9 crore.

Geographically, the business remains overwhelmingly domestic. India accounted for ₹1,463.6 crore of revenue, with international markets contributing about ₹20.5 crore.

That model sets Kuku apart from many Indian content platforms, which have historically depended on advertising or struggled to persuade users to pay. Kuku's growth suggests that a large number of Indian consumers, many outside the biggest cities, will pay small recurring amounts for content in their own languages, delivered in formats designed for mobile phones.

Growth bought with marketing

The growth did not come cheaply. Marketing and advertising expenses rose about fourfold to ₹1,105.1 crore, from ₹284.8 crore in FY25, and accounted for roughly 77.7% of total expenses. Total expenses rose about 3.5 times to ₹1,421.8 crore.

Operational costs rose about elevenfold to ₹96.3 crore, reflecting higher spending on content and platform operations. Employee benefit expenses rose a more modest 24% to ₹74.1 crore.

The figures point to a business that has found a way to convert marketing spend into paying subscribers at a profit, at least at current scale. The central question for investors is how durable that conversion is. If retention is high, today's acquisition spending builds a base of recurring revenue that becomes more profitable over time. If churn is high, the company will need to keep spending heavily just to stand still.

Kuku ended the year with a stronger balance sheet, with cash and bank balances rising about 2.5 times to roughly ₹293 crore.
8ff0f621-838f-42fd-b912-46829a1b4fe5 (1).png

The microdrama bet

The most significant driver of Kuku's recent growth has been microdramas: short, serialised video stories designed to be watched in episodes of a minute or two on a phone screen. The format has grown rapidly in China and among global apps, and Kuku TV is one of the most prominent Indian attempts to localise it.

The company says its portfolio has more than 20,000 content titles across seven languages, over one crore listeners and creators, and about 400 million app downloads.

Microdramas are cheaper to produce than conventional streaming series and lend themselves to cliffhanger-driven, pay-to-unlock or subscription models. They also align with the way younger Indians consume entertainment, in short sessions and largely on mobile data. The risk is that the format attracts intense competition and that user interest proves faddish.

“Kuku has proved it can buy growth profitably. The IPO will test whether it can keep subscribers without spending at the same pace.”
— TIGI Analysis

The road to an IPO

Kuku received approval from the Securities and Exchange Board of India for its proposed public listing in September. The company is expected to raise between ₹2,500 crore and ₹3,500 crore through a mix of fresh shares and an offer for sale, at a valuation reported to be around ₹15,000 crore, or about $1.8 billion.

It has said it plans to use the proceeds for technology and AI infrastructure, content production and geographic expansion. Kuku has raised more than $156 million from investors including Fundamentum Partnership, Krafton, Vertex Ventures, the International Finance Corporation and 3one4 Capital. Its most recent round, an $85 million Series C in October 2025, was led by Granite Asia.

Why public investors will care

Kuku's listing would give public markets a rare pure-play exposure to paid digital content in India, a segment where most large players are subsidiaries of conglomerates or global platforms. ## The unit economics in numbers

A closer look at the ratios shows how much the business has changed in a year. In FY25, Kuku spent more on marketing and advertising than it earned in revenue: about ₹284.8 crore against operating revenue of about ₹241.6 crore. In FY26, marketing fell to roughly 74% of revenue, even as the absolute spend quadrupled.

Its EBITDA margin was about 5.6% of operating revenue, positive but thin. That leaves the company with little room for error if customer acquisition costs rise or competition forces it to spend more on content.

One further detail stands out. Net profit of ₹182.7 crore was higher than profit before tax of ₹88.6 crore, which means the company recorded a tax credit for the year. Investors will want to see how much of future profitability comes from operations rather than accounting items once the company publishes its full offer document.

The company's numbers will be compared with those of other recently listed consumer internet companies, many of which have faced scrutiny over whether their growth is profitable. Kuku can point to a full year of profit. Sceptics will point to the dependence on marketing and to the fact that 99% of revenue comes from a single stream.

Investors will also look for engagement data in the offer document, including subscriber retention, average revenue per paying user and the split of revenue between Kuku FM and Kuku TV, none of which has been detailed in the figures released so far. Those metrics will show whether growth comes from a loyal core audience or from constantly replacing lapsed users.

Timing is another consideration. Indian equities have been under pressure, and several new-age stocks have fallen sharply in recent weeks. A strong listing for Kuku would depend on investors looking past market weakness to the company's growth and margins.

For India's startup ecosystem, the results carry a broader message. Founded to serve audiences in regional languages, Kuku has shown that building for users beyond India's English-speaking metros can produce a business of significant scale. If the IPO goes ahead on the expected terms, it would also add another consumer internet company to the growing list of Indian startups choosing domestic public markets over overseas listings.

TagsKuku FMKuku TVKuku TechnologiesMicrodramaAudio StreamingIPOStartup ProfitabilitySubscription EconomyDigital EntertainmentSEBIIndian StartupsRegional ContentCreator EconomyUnicorn

Reader reviews

Sign in to rate and review this article.
Loading reviews…