DiasporaImpact5 MIN READ

NRI Deposits Surge to a Record $121.94 Billion in Five Months as Banks Tap the Diaspora Under an RBI Swap Window

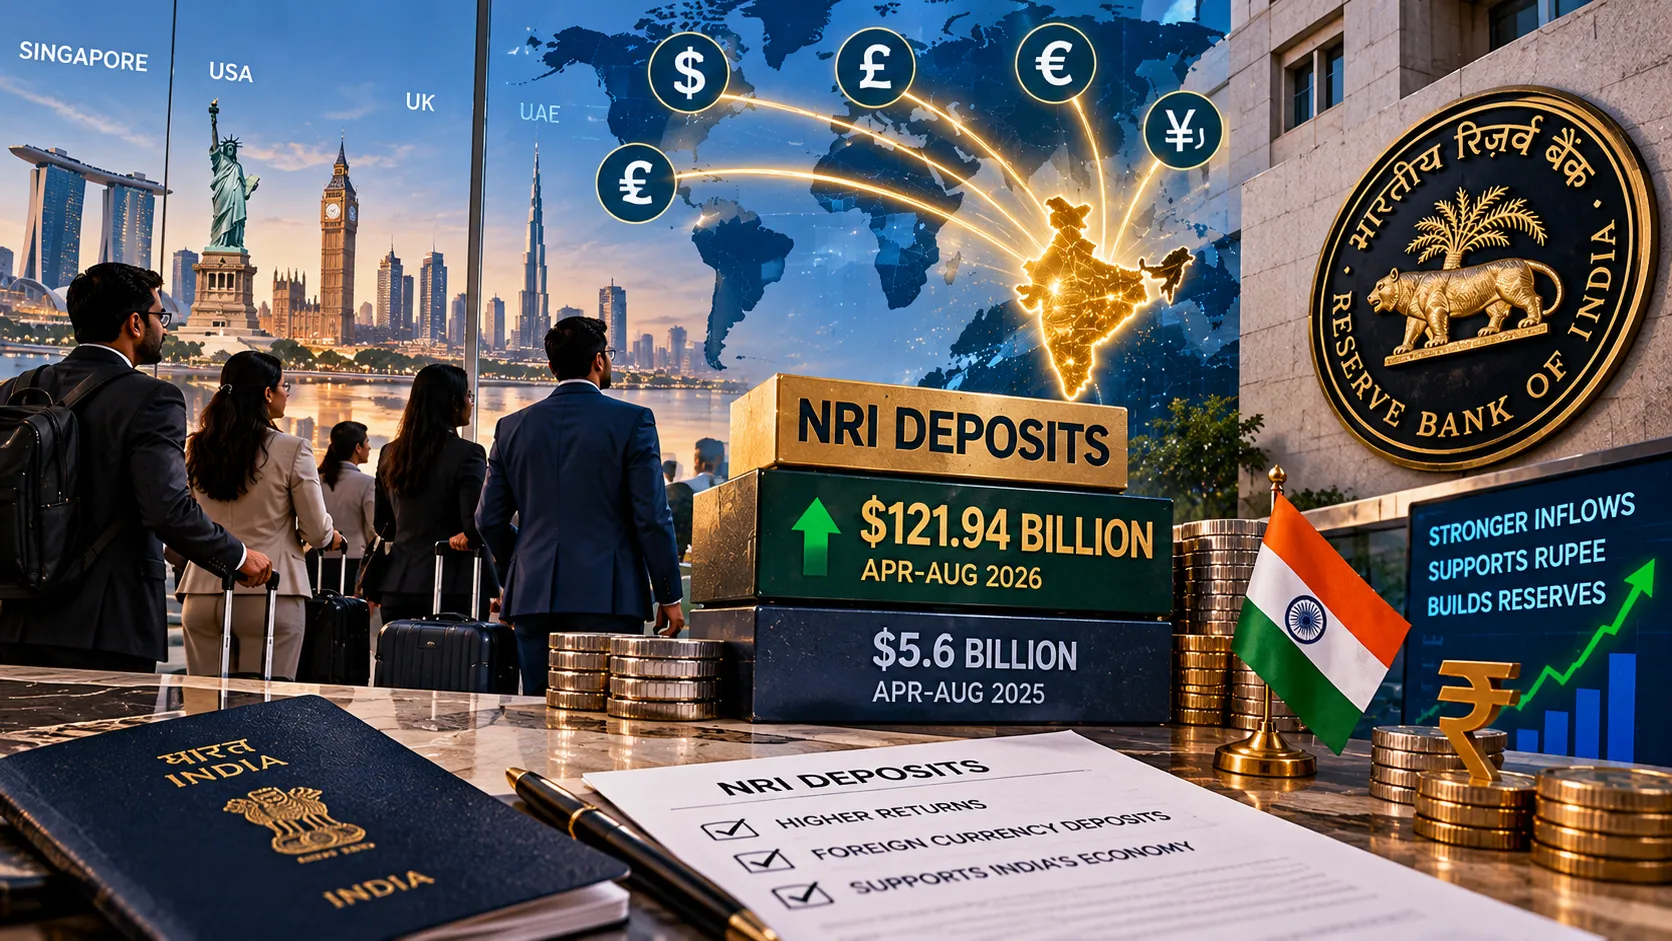
Non-resident Indians deposited a net $121.94 billion in Indian banks in April-August 2026, up from about $5.6 billion a year earlier, RBI data show. Almost all of it came through FCNR(B) foreign currency accounts, after the central bank launched a concessional swap facility in June. Outstanding NRI deposits jumped to $286.48 billion at the end of August.

By Shaym Kumar · Author26 October 2026New
NRI Deposits Surge to a Record $121.94 Billion in Five Months as Banks Tap the Diaspora Under an RBI Swap Window

The global Indian diaspora has poured an unprecedented amount of money into India's banks this year, providing a crucial cushion for the rupee and the country's finances as oil prices surge and foreign portfolio investors pull back.

Inflows into deposit schemes for non-resident Indians (NRIs) reached $121.94 billion in April to August 2026, according to Reserve Bank of India data reported by Business Standard on Friday, October 23. That compares with about $5.6 billion in the same period a year earlier, an increase of more than 21 times.

The outstanding balance of NRI deposits stood at $286.48 billion at the end of August, up from $200.89 billion just a month earlier and $166.80 billion a year before.

The FCNR(B) surge

Almost the entire increase came from Foreign Currency Non-Resident (Bank) deposits, known as FCNR(B) accounts, which allow NRIs to hold deposits in foreign currencies such as the US dollar, pound or euro, without exposure to rupee fluctuations. Inflows into FCNR(B) deposits totalled $120.94 billion in April-August, taking the outstanding balance to $154.69 billion.

By contrast, Non-Resident External (NRE) rupee deposits saw an outflow of $1.29 billion, with outstanding balances slipping to $96.43 billion. Non-Resident Ordinary (NRO) accounts, which hold income earned in India, recorded inflows of $2.29 billion, with balances of $35.35 billion.
0e67039d-9336-4b35-8014-026da16eee96.png

The RBI's swap window

The surge followed a policy move by the RBI. In June 2026, the central bank introduced a concessional foreign exchange swap facility to encourage banks to mobilise foreign currency deposits. Under such arrangements, banks that raise dollar deposits can swap them with the RBI for rupees at favourable rates, reducing their cost of hedging and allowing them to offer attractive interest rates to depositors.

Banks mobilised $133 billion under the facility up to August 31, according to the RBI data. The window allowed banks to raise fresh FCNR deposits until September 30.

The measure echoes a similar scheme in 2013, when the RBI offered a concessional swap window for FCNR(B) deposits during a period of severe pressure on the rupee, the so-called "taper tantrum." That scheme attracted about $34 billion. This year's inflows are far larger, reflecting both the scale of the diaspora's wealth and the attractiveness of the terms.

Why India needed the money

The timing is significant. India has faced pressure on its currency and reserves this year as oil prices surged amid conflict in West Asia, foreign portfolio investors sold Indian equities, and US interest rates climbed. The rupee has weakened to around 95 per dollar.

The RBI made record net dollar purchases of $43.26 billion in August, helped by the deposit inflows, building its reserves to a record $785.7 billion in early September. Since then, reserves have fallen by about $65 billion as the central bank has sold dollars to support the rupee, but the diaspora inflows have provided a crucial buffer.

Why NRIs responded

For NRIs, FCNR(B) deposits offered an attractive combination: interest rates that were competitive with or higher than those available in their countries of residence, no currency risk because deposits are held in foreign currency, and the safety of Indian banks. Interest earned on FCNR(B) and NRE deposits is also exempt from Indian income tax for NRIs, though it may be taxable in their country of residence.
“When India needed dollars, its diaspora answered, and the numbers are unlike anything seen before.”
— TIGI Diaspora Desk

Indian banks marketed the deposits aggressively to NRI customers in the Gulf, the United States, the United Kingdom, Singapore and elsewhere. Banks with large international networks and NRI customer bases, including HDFC Bank, ICICI Bank and State Bank of India, were among the most active.

The diaspora's economic power

The scale of the inflows underlines the economic power of India's global diaspora, one of the largest in the world. India is the world's largest recipient of remittances, receiving well over $100 billion a year from Indians working abroad, particularly in the Gulf states, the United States and the United Kingdom.

Beyond remittances, NRIs invest in Indian property, financial markets and businesses, and many maintain deep financial ties with their families and communities in India. In times of economic stress, the diaspora has repeatedly been a source of support, from the Resurgent India Bonds of 1998 and the India Millennium Deposits of 2000 to the FCNR swap window of 2013.

The costs and risks

The inflows are not without costs. Under the swap arrangement, the RBI effectively bears part of the cost of offering attractive rates to depositors, which could affect its finances. FCNR(B) deposits also create future obligations: when the deposits mature, typically after one to five years, banks must repay them in foreign currency, which could create outflows if depositors do not renew.

Economists also note that deposit-based inflows are a form of borrowing rather than long-term investment. While they help stabilise the currency in the short term, sustained strength requires durable inflows such as foreign direct investment and export earnings.

Data notes

Business Standard noted that the scheme-level figures for the prior-year period do not fully reconcile with the headline comparison of $5.6 billion, so the year-on-year multiple should be treated with some caution. The current-year figures are consistent, with FCNR(B), NRE and NRO flows summing to $121.94 billion.

What it means for NRIs

For NRIs, the episode highlights both the opportunities and the considerations of investing in India. Foreign currency deposits can offer competitive, tax-efficient returns without exchange-rate risk, while rupee deposits offer higher interest rates but carry currency risk. The Financial Stability and Development Council also discussed simplifying digital know-your-customer procedures for NRIs on Friday, which could make it easier for overseas Indians to open and manage accounts.

Remittances and the diaspora economy

The deposit surge comes on top of India's already enormous remittance inflows, which reached record levels in recent years, supported by Indians working in the Gulf, the United States, the United Kingdom, Canada, Singapore and elsewhere. Together, remittances and NRI deposits make the diaspora one of India's largest sources of foreign exchange.

What comes next

With the RBI's swap window having closed at the end of September, inflows are likely to slow in the coming months. Attention will turn to how the deposits are deployed by banks and whether depositors renew them at maturity.

For India, the episode is a powerful reminder that its diaspora remains one of its most valuable economic assets.

TagsNRI depositsFCNR(B)NRENROIndian diasporaRBIswap facilityremittancesforeign currency depositsrupeeforex reservesIndian banksHDFC BankSBIGulf NRIsUS NRIsinterest ratescapital inflowsbalance of paymentsdiaspora investment

Reader reviews

Sign in to rate and review this article.
Loading reviews…