Palantir Technologies reported the strongest quarter in its history. Quarterly revenue topped $2 billion for the first time, and its US commercial business overtook US government work as its largest revenue source. Investors sold the stock anyway.
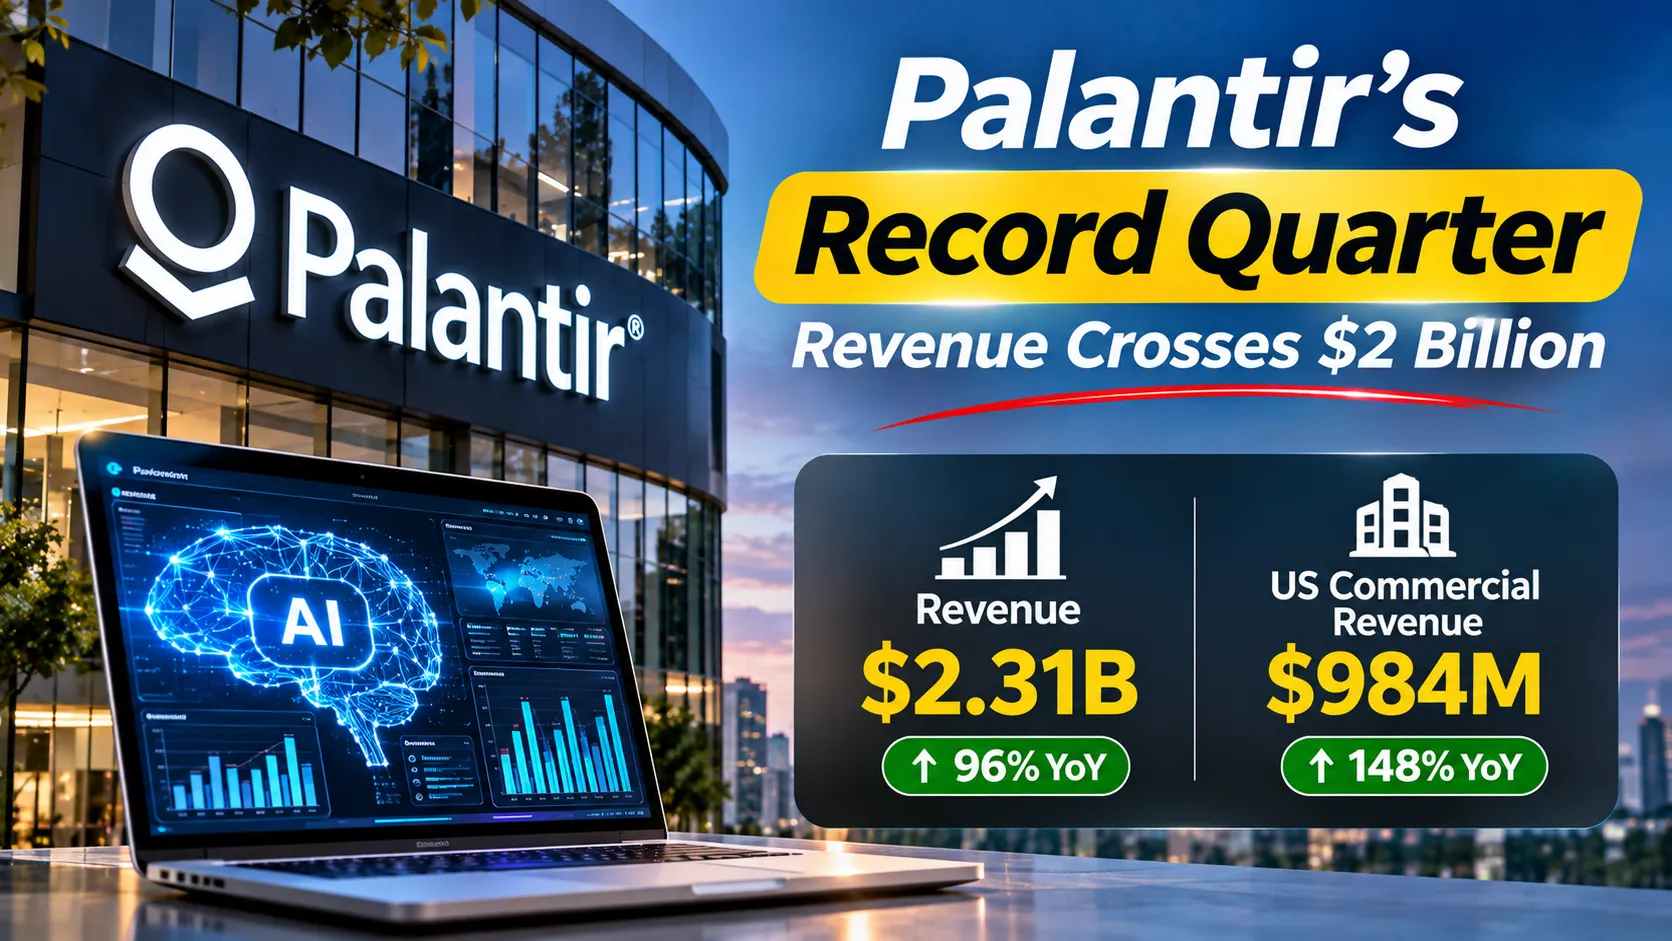
Third-quarter revenue rose 96% year on year and 20% from the previous quarter to $2.313 billion, the company said in its earnings release. Revenue from the United States grew 119% to $1.937 billion.
Within that, US commercial revenue grew 148% year on year to $984 million, surpassing US government revenue of $953 million. Palantir has historically been known primarily as a contractor to defence and intelligence agencies, so this was the first time commercial sales had taken the lead. Government revenue still grew a robust 96%.
Shares of Palantir fell nearly 5% in early trading on Tuesday, November 3, after the results were released after the market close on Monday, making the company one of the session's most notable big-name decliners.
A blowout on almost every measure
The headline figures were extraordinary by the standards of a company of Palantir's size.
Cash from operations reached $1.205 billion, a 52% margin, and adjusted free cash flow was $1.216 billion, a 53% margin. GAAP and adjusted earnings per share were both $0.44.
Palantir closed $1.463 billion of US commercial total contract value (TCV) in the quarter, and its US commercial remaining deal value, a measure of contracted future revenue, reached $6.517 billion, up 79% year on year.
The company's growth has been accelerating for more than two years, driven by demand for its Artificial Intelligence Platform (AIP). AIP lets large organisations deploy AI models on their own data and connect them to operational workflows, from supply chains and manufacturing to finance and customer service.
So why did the stock fall?
The answer lies in one number and in the price investors had already paid.
US commercial TCV, the value of new deals signed in the quarter, rose only 11% year on year to $1.463 billion. For a business whose commercial revenue was growing at nearly 150%, that pace of new bookings looked like a sharp deceleration. Traders focused on the slowdown in new US commercial bookings, as market commentary on the session noted, because bookings are a leading indicator of future revenue. A slower pace of new deals could foreshadow slower revenue growth in coming quarters.
Valuation amplified the reaction. Palantir has been one of the best-performing large stocks of the AI era, and its shares trade at multiples of revenue and earnings far higher than most software peers. At such valuations, investors expect not just strong results but continued acceleration on every key metric. Any sign of deceleration, even amid record numbers, can trigger profit-taking.
The pattern is familiar. In November 2025, Palantir's shares also fell after a quarter in which it beat estimates and raised guidance, as analysts said valuation concerns outweighed operational strength.
The broader AI market mood
Palantir's results landed during a period of heightened anxiety about AI stocks. In the days before, technology shares had sold off on concerns about elevated valuations, enormous AI infrastructure spending and whether that spending will generate adequate returns. The Nasdaq-100 had slipped into correction territory.
On the day Palantir fell, chip stocks rebounded strongly ahead of AMD's results. The divergence shows how investors are differentiating within the AI trade. Hardware suppliers are benefiting from clear, current demand, while software and platform companies face closer scrutiny over whether AI adoption translates into durable, accelerating revenue.
What Palantir's shift to commercial means
The crossover of commercial and government revenue is strategically significant. For most of its history, Palantir was seen as a government contractor. That profile brought stability and deep relationships, but limited the company's addressable market and exposed it to political and budgetary cycles.
Its commercial growth suggests AIP has found a broad market among corporations seeking to put AI to work on their operations. Palantir's approach typically involves intensive engagement with customers, sometimes through short "boot camps" in which its engineers help clients build working AI applications on their own data within days. That has helped convert pilots into large contracts.
A more balanced revenue mix could make Palantir less dependent on government budgets. Its government business remains a critical pillar, however, particularly as defence agencies in the United States and allied countries invest in AI-enabled capabilities.
Risks and debates
Several debates surround the company. Valuation remains the most prominent: even supporters acknowledge that the stock prices in years of very high growth. Customer concentration in large enterprise and government contracts can create lumpiness in bookings. Competition is intensifying as hyperscale cloud providers, data platforms and AI model developers all pitch enterprise AI capabilities.
Palantir's work for defence, immigration and intelligence agencies also continues to draw scrutiny from civil liberties advocates and some investors focused on environmental, social and governance (ESG) criteria. The company has long defended its government work as supporting democratic institutions and national security.
## Guidance and the road ahead
Investors will now look to Palantir's commentary on the fourth quarter and 2027 for reassurance that the bookings slowdown is a matter of timing rather than a trend. Large enterprise contracts can be lumpy, with a few big deals shifting between quarters and distorting year-on-year comparisons. If new US commercial deal value reaccelerates in the coming quarters, the third-quarter dip may come to look like noise. If it does not, the market may conclude that the most explosive phase of AIP adoption is maturing, and that Palantir's growth will settle at lower, though still impressive, rates.
What it means for India
Palantir's growth highlights the shape of enterprise AI demand that Indian technology firms are also chasing. Companies that can combine AI platforms with deep integration into customers' operations, rather than offering generic tools, are capturing the largest budgets. That is a lesson for India's IT services giants and AI-native firms alike as they reposition around AI.
For Indian retail investors, who have increasingly bought US technology stocks through overseas investment platforms, Palantir's post-earnings fall is also a reminder that strong results do not guarantee a rising share price when valuations are stretched.
For now, Palantir has delivered a quarter that would once have seemed unthinkable for the company: more than $2 billion in revenue, a commercial business larger than its government arm, and cash margins above 50%. The market's verdict is that it must keep accelerating to justify its price.