FundingLatest Deals5 MIN READ

PaleBlueDot AI Raises $200 Million at a $3.2 Billion Valuation, Betting on the Scarcity of AI Compute

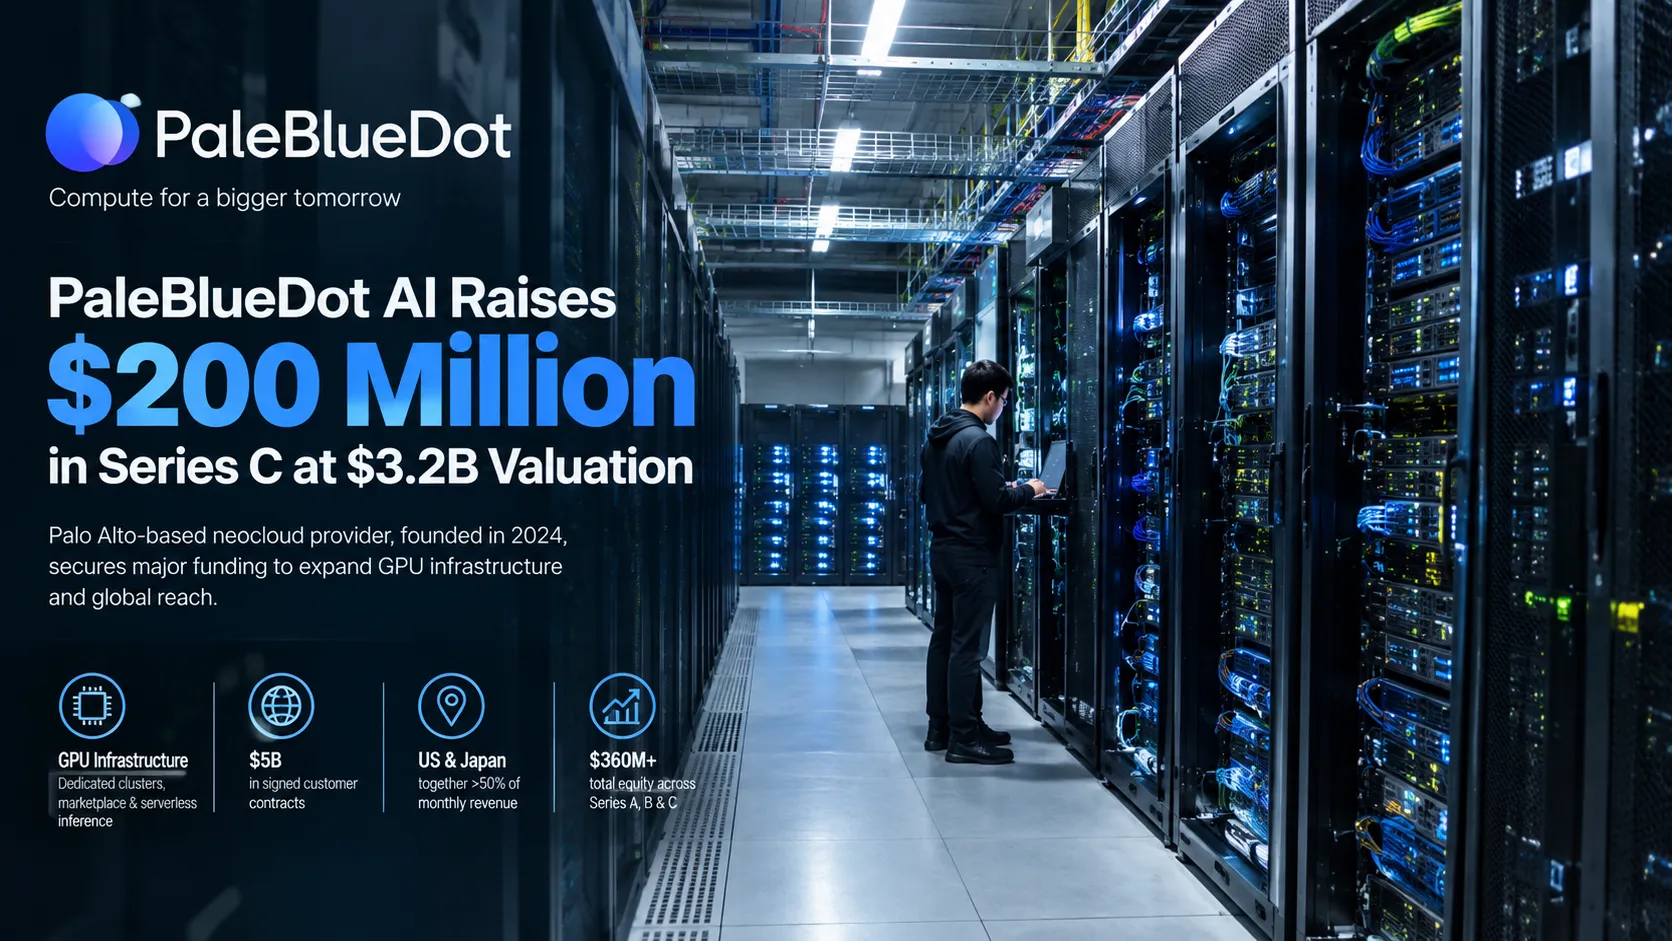
Palo Alto-based PaleBlueDot AI has raised a $200 million Series C led by ComputeCore at a $3.2 billion valuation, saying it has signed more than $5 billion in customer contracts for GPU capacity.

3 October 2026New
PaleBlueDot AI Raises $200 Million at a $3.2 Billion Valuation, Betting on the Scarcity of AI Compute

Investors are still willing to write very large cheques for one part of the artificial intelligence economy: the computing power that runs it. PaleBlueDot AI, a Palo Alto-based provider of GPU infrastructure founded only in 2024, has raised $200 million in a Series C round that values the company at $3.2 billion.

The round was led by ComputeCore, with participation from existing shareholder B Capital and other global investors, according to the company's announcement on 1 October (2 October in India) and a funding analysis by TechStartups. The new valuation is more than three times the roughly $1 billion at which the company was valued around its Series B in January, when it raised $150 million.

PaleBlueDot said it had signed more than $5 billion in customer contracts by 30 September, with the United States and Japan together accounting for more than half of its monthly revenue. It plans to use the new capital to add compute capacity across more locations and hardware configurations and to expand its engineering and commercial teams.

On a day when most venture deals were modest in size, PaleBlueDot's raise accounted for almost all of the capital in newly announced rounds tracked by TechStartups, a sign of how concentrated investor appetite has become

around AI infrastructure.

What PaleBlueDot sells

PaleBlueDot operates in a category often described as "neocloud": companies that specialise in providing access to graphics processing units, the chips that train and run AI models, outside the traditional hyperscale cloud providers such as Amazon Web Services, Microsoft Azure and Google Cloud.

Its business has three parts. It runs dedicated GPU clusters that customers can rent. It operates a marketplace that connects customers with GPU capacity supplied by third-party providers. And it offers serverless inference, which lets customers run AI models without managing the underlying hardware.

That mix gives the company several ways to make money without owning every chip that serves its customers. The marketplace model, in particular, allows it to meet demand spikes by routing work to partners' hardware, reducing the capital it needs to commit upfront.

PaleBlueDot's B300 cluster in Japan, built on one of Nvidia's latest-generation chips, recently received Nvidia Exemplar Cloud status, a designation that benchmarks infrastructure against Nvidia's reference standards. Such certifications matter to customers who need confidence that clusters will perform reliably for large training runs.
Neon Data Consolidation Network.png

The demand behind the valuation

The case for companies like PaleBlueDot rests on a simple observation: demand for AI compute has outstripped supply. Frontier AI laboratories, enterprises building their own models and startups deploying AI applications all need access to large blocks of GPUs, often on short notice. Building a data centre takes years, and the largest cloud providers allocate scarce capacity to their biggest customers first.

Neoclouds fill the gap. They can stand up clusters faster, offer more flexible contracts and specialise in the configurations AI workloads require. The sector has produced several fast-growing companies, and investors have backed them with large equity rounds and debt facilities.

PaleBlueDot's reported $5 billion in signed contracts is an unusually large figure for a company founded just two years ago. If those contracts convert into revenue as expected, they would support a valuation well above where many software companies of a similar age trade.


“Signed contracts are not the same as recognised revenue, cash collected or profit.”
— TIGI Analysis

Contracts are not revenue

That conversion is the key question. Signed contracts are not the same as recognised revenue, cash collected or profit. PaleBlueDot has not disclosed the duration of its contracts, their margins, the delivery obligations attached to them or the capital it will need to fulfil them.

GPU infrastructure is extremely capital-intensive. Chips and the servers, networking and cooling around them cost enormous sums, and data centre space and electricity have themselves become scarce in many markets. Hardware also depreciates quickly: each new generation of Nvidia chips makes the previous one less valuable, and customers may push for upgrades as soon as new hardware becomes available.

The economics therefore depend on utilisation. A cluster that runs near full capacity on long-term contracts at good prices can generate strong returns. One that sits partly idle, or whose customers renegotiate when cheaper capacity appears, can quickly become a financial burden. Investors in PaleBlueDot are underwriting both the strength of demand and the company's ability to execute a complex, capital-heavy build-out.

The company has also used credit financing alongside equity, a common approach among neoclouds that borrow against contracted revenue or the hardware itself. Disclosed equity across its Series A, B and C rounds totals at least $360 million.

A crowded race for compute

PaleBlueDot is not alone. Several larger GPU cloud providers have raised billions of dollars in equity and debt, and some have gone public. Hyperscalers, meanwhile, are spending unprecedented amounts on their own data centres, and chipmakers are deepening relationships with cloud partners to secure distribution for their products.

The broader AI infrastructure build-out has also shown signs of strain. Oracle recently invoked force majeure on a massive data centre campus in New Mexico, rattling investors. Concerns about power availability, construction delays and the eventual return on AI spending have periodically weighed on the sector. For founders building AI applications, the growth of independent compute providers is broadly positive. More suppliers mean more choice, potentially lower prices and less dependence on a handful of hyperscalers that also compete in AI models and applications. Startups that once waited months for GPU allocations can increasingly find capacity on shorter notice.

Why it matters for India

For India, the rise of companies like PaleBlueDot is relevant in two ways. First, Indian AI developers and enterprises are among the customers competing for scarce GPU capacity, and a more diverse set of providers can help them access compute on better terms. Second, India is trying to build its own AI infrastructure through public programmes and private investment, including proposed large data centre and sovereign AI campuses. The global neocloud model offers both a template and a source of competition for those efforts.

The bottom line

PaleBlueDot's raise shows that, for now, the market rewards ownership of scarce compute. A company that did not exist three years ago is valued at more than $3 billion because it can deliver GPUs to customers who need them urgently.

Whether that value holds will depend on execution: building capacity on time, keeping utilisation high, managing hardware cycles and converting a striking contract book into durable profits. The $200 million is a vote of confidence in the demand. The next two years will show whether the economics are just as strong.

TagsPaleBlueDot AIAI InfrastructureGPU CloudSeries CComputeCoreB CapitalNvidiaData CentresNeocloudArtificial IntelligenceVenture CapitalFundingJapanCompute

Reader reviews

Sign in to rate and review this article.
Loading reviews…
