The Philadelphia Semiconductor Index tumbled 5.9% in a single trading session, with Nvidia Corp shares dropping 3.4% and Intel Corp falling 5.6%, marking one of the sharper single-day declines for chip stocks this year as concerns about the pace of AI industry development compounded with rising Treasury yields to trigger a broad selloff across semiconductor equities. The scale of the decline placed considerable pressure on a sector that has served as one of the primary beneficiaries and bellwethers of the broader AI infrastructure investment boom that has powered much of the technology sector's market performance through 2026, making the semiconductor index's sharp pullback a particularly closely watched signal for broader market sentiment toward the sustainability of AI-related equity valuations. The selloff's timing, occurring in the same trading window as cautionary commentary from prominent AI industry leaders about the pace of AI development outstripping the industry's risk management capacity, suggests investors moved quickly to reprice semiconductor equities specifically, given how directly chip company revenue and growth expectations have become tied to continued, uninterrupted expansion of AI infrastructure spending by major cloud providers and AI companies.
Nvidia's 3.4% decline, while meaningful in absolute terms given the company's enormous market capitalisation and outsized influence on broader index performance, was notably more modest than the semiconductor sector's overall 5.9% index decline, suggesting investors differentiated between Nvidia's position as the dominant AI training chip supplier with continued strong demand visibility and the broader semiconductor sector, where companies with less differentiated AI exposure or greater sensitivity to more cyclical, non-AI-related chip demand categories bore a proportionally larger share of the session's selling pressure. Intel's steeper 5.6% decline reflects the company's more complex competitive positioning within the current AI-driven semiconductor cycle, given Intel's historically more limited exposure to the AI training chip category where Nvidia has maintained dominant market share, combined with the company's own ongoing operational and competitive challenges within its core semiconductor manufacturing and design businesses that have made Intel's stock performance considerably more volatile than better-positioned AI-exposed semiconductor peers over recent quarters.
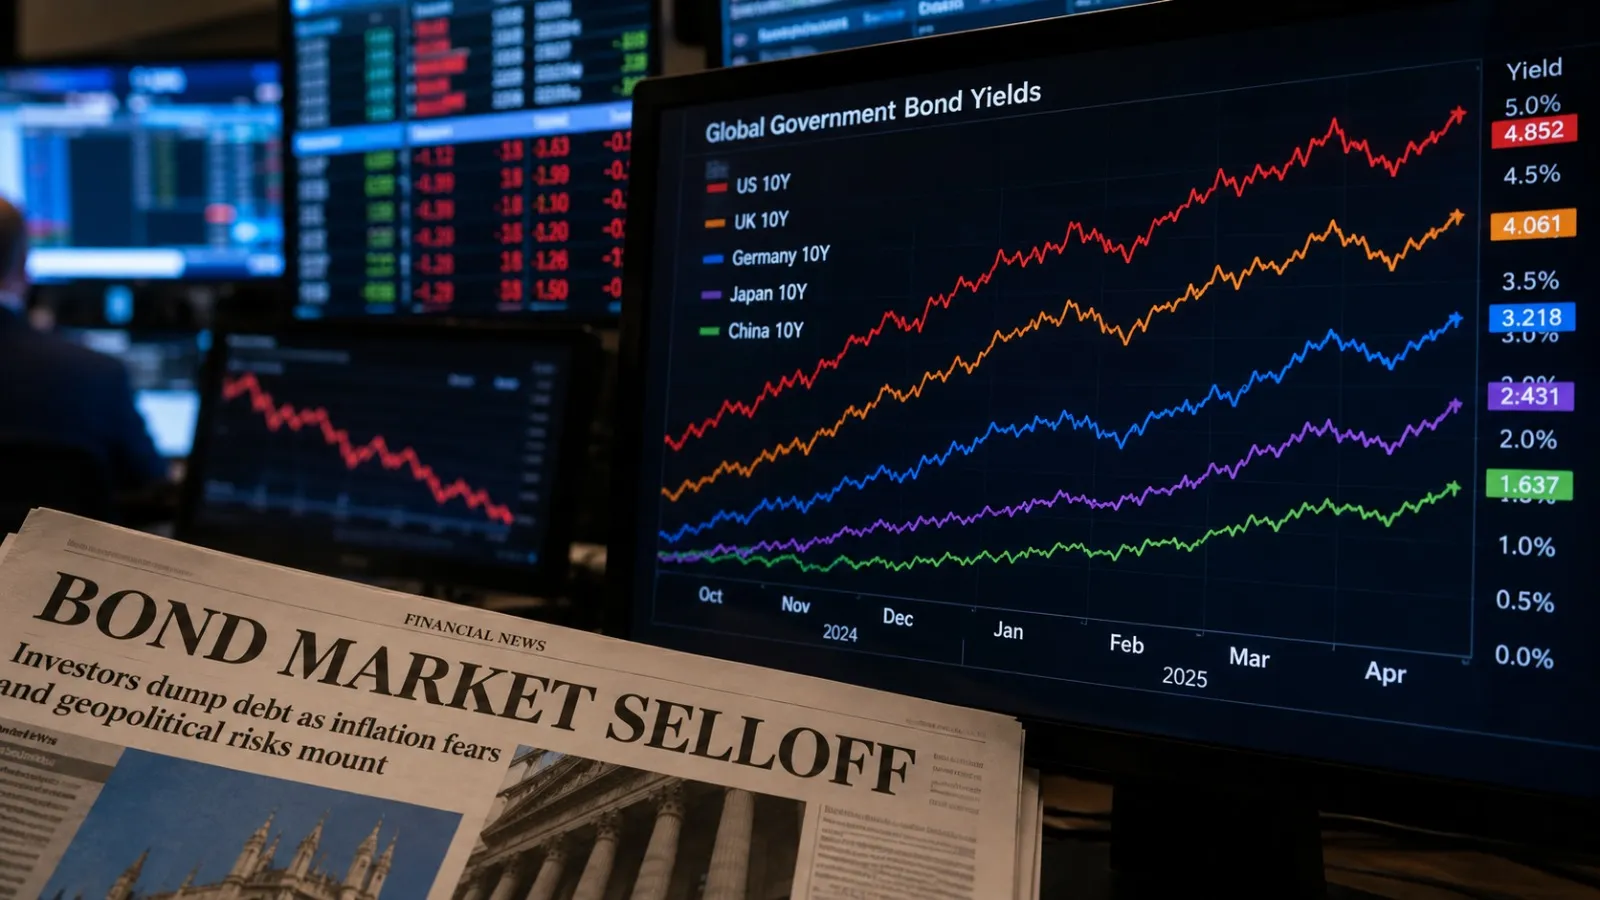
The semiconductor sector's sharp decline arrived alongside a broader combination of negative market catalysts during the same trading session, including the 10-year Treasury yield's breach of the 5% threshold for the first time since 2007, a development that mechanically pressures growth-oriented technology equity valuations given the higher discount rates elevated Treasury yields imply for the kind of distant future earnings growth that semiconductor and broader AI-exposed technology valuations have increasingly depended upon to justify current elevated pricing levels. This combination of AI development pace concerns and rising interest rates created a particularly challenging environment for semiconductor equities specifically, given the sector's dual exposure to both AI sentiment risk and interest-rate-sensitive growth valuation dynamics. Options market activity across major semiconductor names showed elevated demand for downside protection in the sessions surrounding this decline, according to derivatives market data, suggesting institutional investors had begun actively hedging against the possibility of further near-term volatility within the sector even before the full scale of this particular session's decline became apparent, a positioning shift that reflects growing institutional caution about semiconductor valuations after a multi-year period of substantial AI-driven sector outperformance.
For the broader AI infrastructure investment narrative, the semiconductor sector's sharp single-session decline raises important questions about how durable investor confidence in continued AI infrastructure spending growth remains, given that semiconductor companies' revenue and earnings trajectories depend directly on hyperscale cloud providers and AI companies maintaining or accelerating their current pace of capital expenditure on AI training and inference infrastructure. Any sustained moderation in this spending trajectory, whether driven by the kind of AI development pacing concerns that have recently surfaced or by broader macroeconomic pressures including elevated interest rates increasing the cost of capital for infrastructure investment, would carry direct and substantial implications for semiconductor company financial performance. As markets absorb this latest semiconductor sector decline, investors will likely watch closely for how major chip companies address these concerns in subsequent earnings calls and guidance updates, given that management commentary on order backlogs, customer capital expenditure plans and broader AI infrastructure demand visibility will provide the most direct evidence available for whether this session's sharp selloff reflects a genuine shift in the underlying AI infrastructure spending trajectory or a shorter-term sentiment-driven repricing that may prove less durable than the scale of the single-session decline might initially suggest. Several semiconductor equipment and materials suppliers further down the AI hardware supply chain also saw meaningful share price declines during the same trading session, illustrating how the sector-wide selloff extended beyond the most prominent chip designers like Nvidia and Intel to affect the broader ecosystem of companies supplying manufacturing equipment, specialised materials and testing infrastructure that the semiconductor industry's AI-driven expansion has depended upon, a broader sector impact that suggests investors were repricing AI infrastructure spending expectations across the full semiconductor value chain rather than reacting to company-specific concerns at any single firm. Analysts covering the semiconductor sector have generally cautioned that single-session declines of this magnitude, while notable, do not necessarily indicate a fundamental shift in underlying AI infrastructure demand trends, pointing to the sector's history of periodic sharp pullbacks driven by sentiment shifts that have subsequently reversed once subsequent earnings reports or customer capital expenditure guidance reaffirmed continued strong underlying demand, a pattern that will only become clear as the relevant companies report their next quarterly results and provide updated forward guidance. Semiconductor equipment makers serving the broader chip manufacturing supply chain have generally maintained their own forward order guidance despite the sharp equity selloff, a divergence between near-term stock price action and underlying order book commentary that some analysts point to as evidence the decline reflects sentiment repricing rather than a fundamental demand shift. Retail investor trading activity in semiconductor stocks reportedly spiked during the session, according to several brokerage platforms, with mixed positioning between investors treating the decline as a buying opportunity given continued long-term AI infrastructure demand conviction and others reducing exposure amid the broader uncertainty the session's cautionary AI commentary introduced. Historical data on comparable single-session semiconductor index declines shows a mixed record of subsequent recovery timelines, ranging from swift rebounds within days to more prolonged consolidation periods extending several weeks.