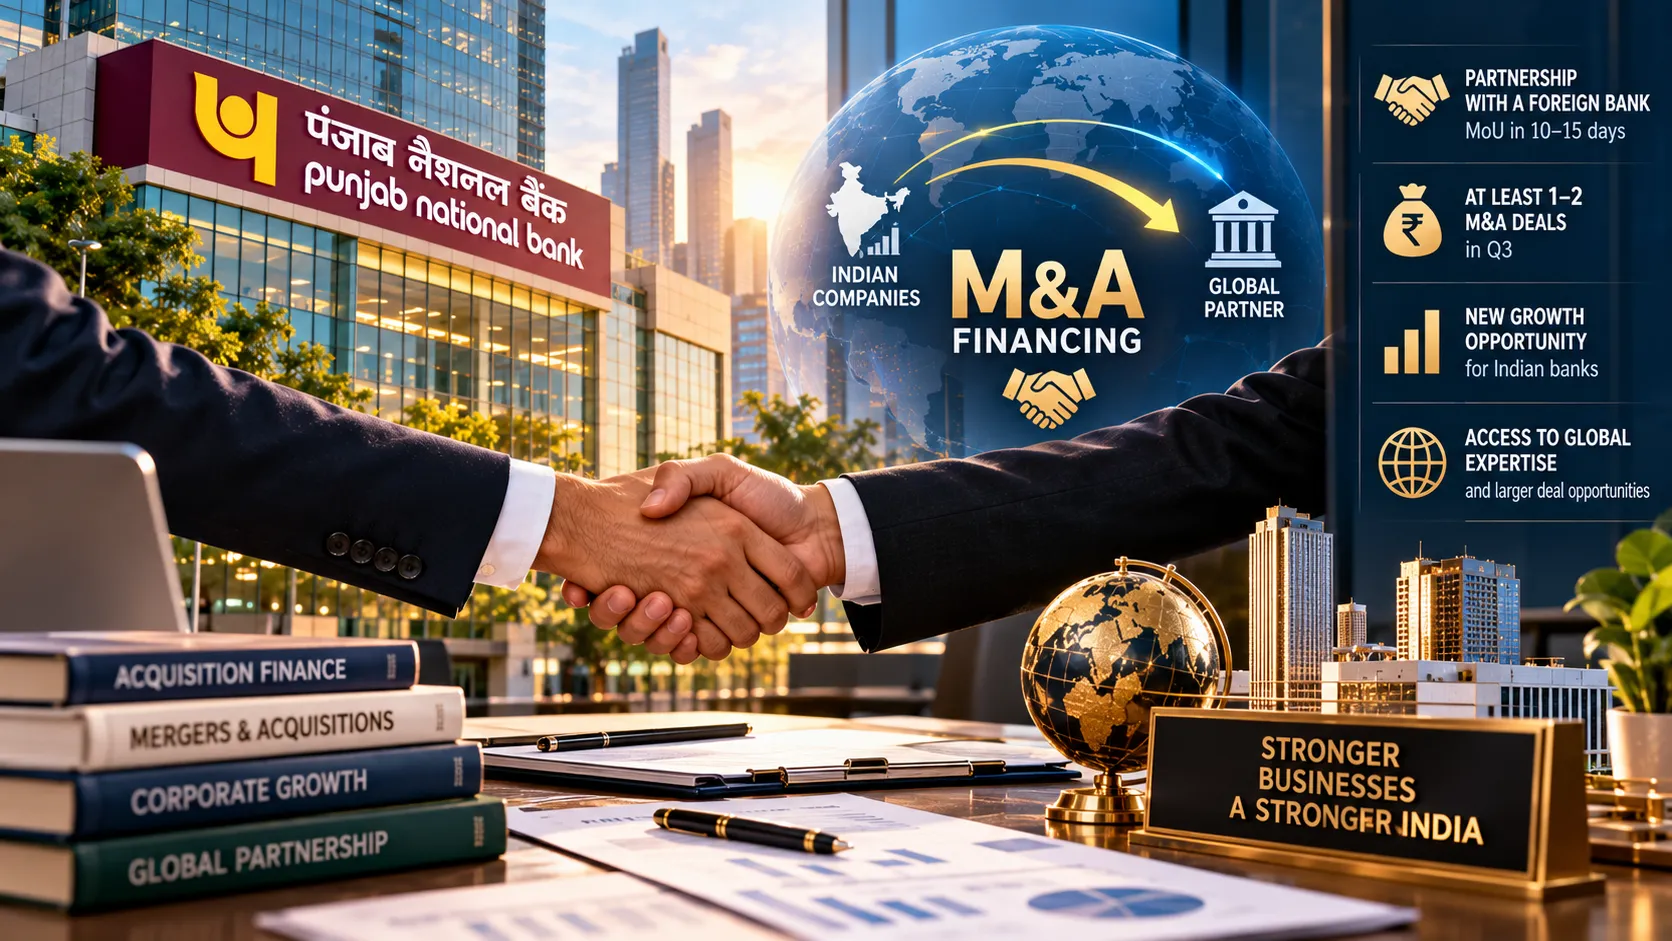
Punjab National Bank, India's second-largest state-owned lender, is preparing to enter the business of financing corporate takeovers in partnership with a foreign bank, in a sign of how Indian public sector banks are seeking new sources of growth.
PNB's managing director and chief executive, Ashok Chandra, said the bank expects to finalise a memorandum of understanding with a foreign lender within the next 10 to 15 days to collaborate on financing mergers and acquisitions. The agreement is currently being vetted. Chandra declined to name the foreign bank "as of now," according to an interview published by Business Standard on October 18.
PNB is at an advanced stage of discussions with only this one bank, Chandra said, and plans to complete the agreement before deciding on next steps. The bank expects to finance at least one or two M&A transactions in the third quarter of the financial year, which runs from October to December.
A new market for Indian banks
Acquisition finance, in which lenders provide funds to companies buying other businesses, has traditionally been a small part of Indian banks' operations. Regulations long restricted Indian banks from financing the purchase of shares in other companies, leaving much of the business to foreign banks and non-bank lenders, and pushing Indian companies to raise acquisition debt overseas.
Recent regulatory changes have opened the door wider for domestic banks to participate in such deals. With Indian companies increasingly active in domestic consolidation and overseas acquisitions, acquisition finance offers banks the prospect of large, high-quality corporate loans and fee income.
Partnering with a foreign bank could give PNB access to expertise in structuring complex deals, as well as relationships with global companies and investors. For a foreign bank, a partnership with one of India's largest lenders offers access to PNB's balance sheet and domestic corporate relationships.
Mixed second-quarter results
The comments came after PNB reported results for the July-to-September quarter. The bank's operating profit grew 4.2% in the second quarter and 5.2% in the first half of the year, below its full-year guidance of 9% to 10%. Chandra attributed the shortfall to subdued treasury income, as rising bond yields reduced gains on the bank's investment portfolio.
Core operating profit, which excludes treasury income and recoveries, was stronger, rising 29% year on year, following growth of more than 32% in the previous quarter. Chandra said he was "very confident" of meeting the bank's operating profit guidance for the year and named growth of 20% to 30% in core operating profit as his top priority.
The bank's current and savings account (CASA) ratio, a measure of low-cost deposits, stood at 36.6%, below its 38% guidance. Chandra expects it to reach 36% to 37% by March, with CASA deposits growing about 8%, as institutional deposits decline.
Credit growth and liquidity
PNB's loan book is growing at 12% to 13%. Its credit-to-deposit ratio is about 75%, and its liquidity coverage ratio is 133%, giving the bank room to grow lending in line with deposits.
Following the Reserve Bank of India's recent repo rate hike, PNB will decide on repricing its deposits at the end of October. Chandra said the bank was "not in a hurry" because it has ample liquidity.
The bank also flagged pressure from regulatory changes affecting fee income. PNB earns about ₹350 crore a year from bancassurance, the sale of insurance products through its branches, and expects an 8% to 9% decline in that income under draft norms from the insurance regulator IRDAI. On payments, Chandra noted that about 96% of UPI transactions are below ₹2,000 or otherwise exempt from a proposed merchant discount rate levy.
Asset quality and the shift to expected credit loss
Asset quality continued to improve. PNB's slippage ratio, the rate at which loans turn bad, was 0.77%, below its guidance ceiling of 0.9%. Accounts flagged as special mention, an early warning category, made up about 2.5% of the portfolio. Gross and net non-performing assets both declined, and the credit cost was 0.25%.
There were some pockets of stress. Slippages in agricultural loans nearly doubled in the quarter due to delayed renewals, and management said it has strengthened credit monitoring.
PNB is also preparing for the move to an expected credit loss (ECL) framework, under which banks must set aside provisions based on expected future losses rather than losses already incurred. The migration begins in April 2027. PNB holds ₹2,560 crore in floating provisions and set aside another ₹1,150 crore against standard assets in the second quarter. Chandra said the remaining requirement is about ₹4,500 crore, which the bank can meet over five years.
The bank's capital adequacy ratio is 18%. Even if PNB made the full ECL provision in a single year, Chandra said, the ratio would fall to about 17.5%, well above regulatory requirements.
Public sector banks in favour
PNB's ambitions reflect the turnaround of India's state-owned banks. After years of heavy bad loans and losses, public sector lenders have cleaned up their balance sheets, returned to profitability and rebuilt capital. Investors have taken notice: on October 19, the Nifty PSU Bank index was the best-performing sector in early trade, even as private sector bank shares fell.
Entering new businesses such as acquisition finance is part of their effort to compete with private sector rivals and foreign banks for high-value corporate business.
How acquisition finance works
In a typical acquisition finance transaction, a bank provides a loan to a company or a special-purpose vehicle to fund the purchase of another business. The loan is usually secured on the shares or assets of the target and repaid from the combined company's cash flows. Because such loans can be large and complex, banks often form syndicates to share the risk.
For Indian companies, access to domestic acquisition finance could reduce reliance on overseas borrowing and the associated currency risks. Large Indian conglomerates have been active acquirers at home and abroad, in sectors ranging from cement and steel to consumer goods and technology, creating a sizeable potential market for lenders able to structure such deals.
What to watch
The signing of the MoU and the identity of the foreign bank will be the next milestone. The first M&A deals that PNB finances will show how much appetite it has for large, complex transactions and how it manages the risks involved.
For India's corporate sector, more competition in acquisition finance could lower borrowing costs and make it easier for companies to pursue consolidation at home and acquisitions abroad. For PNB, success in the business would diversify its earnings at a time when treasury income is under pressure and the transition to ECL will require careful management of capital.