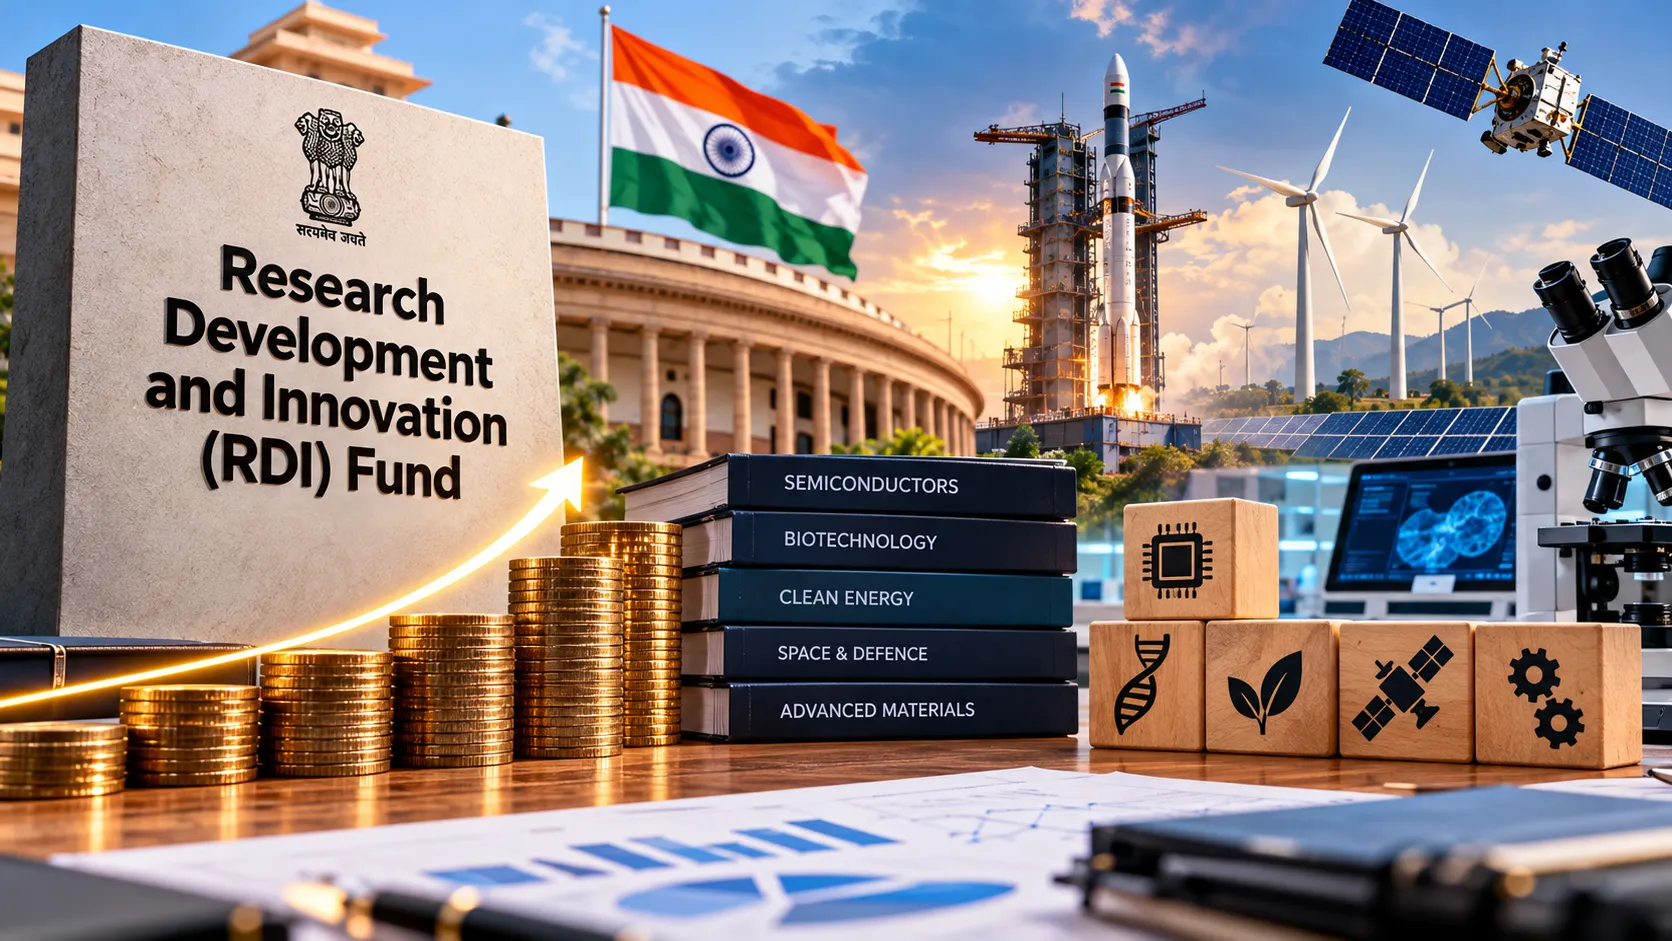
India’s ₹1 lakh crore Research, Development and Innovation (RDI) Fund has approved 19 second-level fund managers and committed ₹7,131 crore to them, its biggest step yet towards channelling government capital into deep-technology companies. The approvals were cleared by the Empowered Group of Secretaries (EGoS) overseeing the scheme, which also added five technology areas to the list eligible for support.
The 19 approved managers comprise 14 alternative investment funds (AIFs) and five focused research organisations (FROs). Each will be required to mobilise matching private capital, so that public money crowds in investors instead of replacing them. The scheme targets enterprises at technology readiness level (TRL) 4 and above, the point at which a technology has been validated in the lab but still needs significant capital and time to reach the market.
The decision comes as India tries to close one of its most persistent gaps: the shortage of long-term, risk-tolerant capital for companies building in semiconductors, advanced materials, space, defence, quantum, biotechnology and clean energy.
How the fund works
The RDI Fund was launched in November 2025 under the Anusandhan National Research Foundation (ANRF) and the Department of Science and Technology. Its design is deliberately indirect. Instead of the government picking companies, the fund allocates capital to second-level managers, professional venture funds and research organisations that then select and invest in individual enterprises.
That model draws on lessons from India’s Fund of Funds for Startups, administered by SIDBI, which has backed dozens of venture funds over the past decade. Using private managers is meant to bring market discipline, sector expertise and faster decision-making than a ministry could manage directly, while the matching requirement ensures private investors share the risk.
The inclusion of focused research organisations is a newer feature. FROs are mission-driven entities designed to tackle specific scientific or engineering problems that are too large for a startup and too applied for a university lab. Giving them access to RDI capital signals that the government sees value in funding the research-to-product pipeline, not just companies that are already investable.
Deeptech momentum
The approvals land at a moment of rising investor interest. Deeptech funding in India rose 176% year-on-year in the third quarter of 2026 to $290 million across 28 deals, according to industry data cited by Inc42, while the broader startup ecosystem grew just 5% to $2.2 billion over the same period.
That divergence reflects both policy and market forces. Government programmes in semiconductors, space and defence have created anchor customers and incentives, and global investors have been looking for exposure to India’s manufacturing and supply-chain ambitions. Public-market listings such as the upcoming IPO of defence-electronics maker Tonbo Imaging are also beginning to offer exit routes that deeptech investors have long lacked.
The governance debate
The fund’s progress has not been free of controversy. The Indian Express reported that about two-thirds of the more than ₹2,000 crore already allocated by the fund had gone to entities linked to members of its selection panels. The report has prompted questions about conflicts of interest and the transparency of the selection process.
Investor opinion is divided. A survey of 85 investors conducted by Inc42 found that 52% believed the fund’s existing safeguards were adequate, while 25% described the situation as a governance failure. The remainder were undecided or held mixed views.
Some overlap between panel members and recipients is arguably inevitable in a small ecosystem. India’s pool of experienced deeptech investors and technologists is limited, and the people best qualified to evaluate proposals are often connected to the funds and institutions applying for capital. The critical question is whether conflicts are disclosed and whether conflicted members recuse themselves from decisions.
Those safeguards matter for more than appearances. A public fund of this scale depends on credibility with private investors, whose matching capital it needs, and with founders, who must believe allocations are made on merit. Clear disclosure of recusals, selection criteria and investment outcomes would go a long way towards settling the debate.
Why patient capital matters
The case for a fund of this kind rests on a structural gap. Deeptech companies typically need many years and large sums to move from prototype to product, and they often require expensive equipment, testing facilities and regulatory approvals along the way. Conventional venture funds, which usually expect returns within seven to ten years and favour fast-scaling software businesses, have historically been reluctant to fund such companies in India.
As a result, many promising Indian research teams have either stalled at the prototype stage or moved abroad to raise capital. Founders in semiconductors, advanced materials and biotechnology have frequently cited the lack of domestic risk capital at the technology-validation stage as a key constraint.
India’s spending on research and development has also remained low by international standards, at well under 1% of GDP, compared with more than 2% in China and more than 3% in the United States. Private-sector R&D is particularly thin. Policymakers hope that the RDI Fund, by sharing risk with private investors, will draw more corporate and financial capital into research-intensive businesses.
The matching requirement is central to that ambition. If each rupee of public money mobilises at least one rupee of private capital, the fund’s effective firepower doubles. But it also means the pace of deployment depends on how quickly second-level managers can persuade private investors, many of whom remain cautious about long-gestation technologies, to commit alongside the government.
The scheme, as approved by the Union Cabinet, also allows long-term financing at low or nil interest rates alongside equity, an acknowledgement that many deeptech companies need patient, flexible capital rather than only venture-style stakes.
What comes next
With managers approved, attention will shift to deployment. The ₹7,131 crore committed so far is a small fraction of the fund’s ₹1 lakh crore corpus, and the speed at which second-level managers raise matching capital and invest will determine whether the scheme accelerates India’s deeptech ecosystem or becomes another slow-moving government programme.
The newly added technology areas also give founders in adjacent fields a route to capital, though details of how each manager will target specific sectors are still emerging.
For investors, policymakers and diaspora technologists watching India’s ambitions in strategic technologies, the RDI Fund is one of the most consequential experiments in Indian industrial policy this decade. Its real test is not how quickly it commits capital, but whether its processes command the trust of the founders and investors it is meant to serve. If it gets that right, it could fill a gap that has held back Indian research commercialisation for decades.