India's markets regulator is developing a second layer of surveillance designed to identify and eventually remove bad actors among listed companies, a senior official said, in a move that signals a tougher approach to the governance problems that have accompanied the country's retail investing boom.
Kamlesh Chandra Varshney, a Whole-Time Member of the Securities and Exchange Board of India (SEBI) who oversees corporate finance and market surveillance, said the regulator was working on a secondary surveillance framework aimed at listed companies, PTI reported. Speaking at an industry event, Varshney also said SEBI was taking steps to flag high-risk small initial public offerings in order to protect retail investors from potential losses.
The remarks come at a time when Indian companies have raised record sums from equity markets and when millions of first-time investors have entered the market through mobile trading apps.
From market surveillance to company surveillance
SEBI and the stock exchanges already operate extensive market surveillance systems. These monitor trading for signs of manipulation, insider trading and unusual price or volume movements. Tools such as the Additional Surveillance Measure and Graded Surveillance Measure frameworks place restrictions on trading in stocks that show signs of abnormal activity.
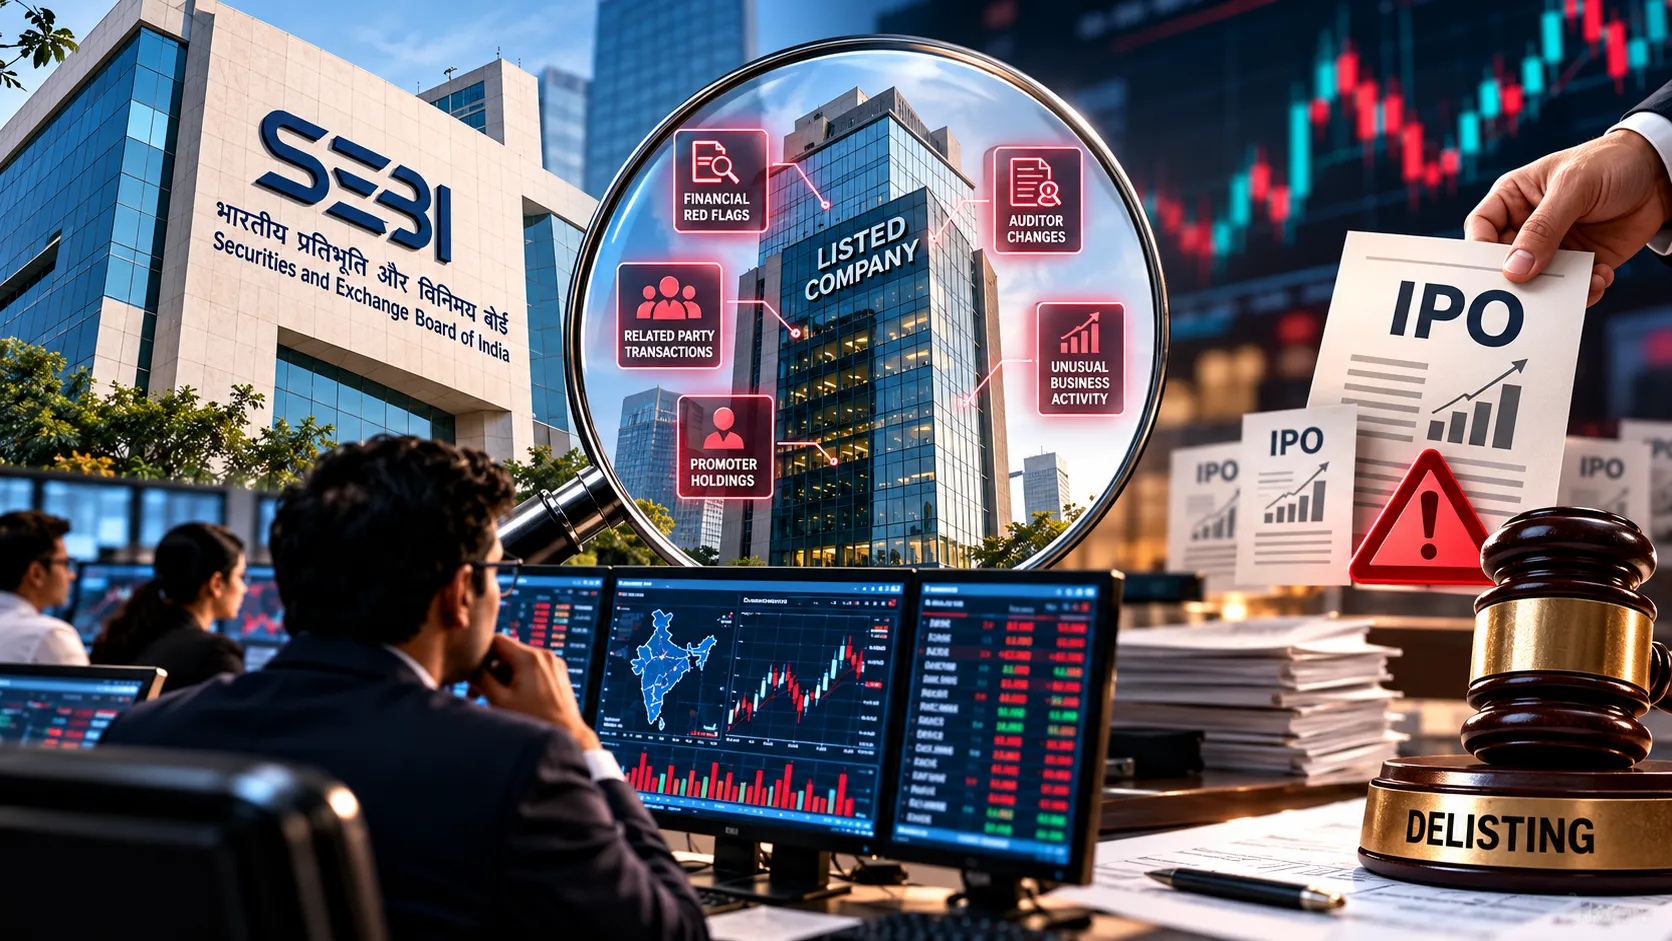
What Varshney described goes further. A second surveillance system focused on listed companies themselves would look beyond trading patterns to the behaviour and fundamentals of the issuers. That might include financial reporting red flags, related-party transactions, frequent changes in auditors, unexplained movements in promoter holdings or business activity that does not match reported revenues.
The stated aim, to identify and ultimately remove bad actors, implies that the framework could feed into enforcement actions, trading restrictions or, in serious cases, compulsory delisting. SEBI has not yet published the design of the system or a timeline for its introduction.
The small IPO problem
The second part of Varshney's remarks concerns small IPOs, particularly on the SME platforms of the stock exchanges. These offerings, often worth a few crore rupees, have attracted extraordinary retail demand in recent years, with some oversubscribed dozens or even hundreds of times within hours of opening.
Regulators and market participants have raised concerns that some of these issues involve inflated valuations, weak fundamentals or business models that appear designed mainly to take advantage of retail enthusiasm. When such stocks fall after listing, retail investors are typically the ones left holding losses.
SEBI has already tightened rules on SME listings, including stricter eligibility criteria and closer scrutiny of offer documents. Flagging high-risk issues, as Varshney described, would add a layer of disclosure intended to make investors pause before applying.
Why it matters now
India's equity market has become one of the most retail-driven in the world. Domestic investors, through mutual fund systematic investment plans and direct equity holdings, have become a counterweight to foreign selling. That was visible last week, when domestic institutions bought about ₹33,455 crore of equities while foreign investors sold nearly ₹34,966 crore.
That dependence on domestic retail capital is a strength, but it also creates a vulnerability. If a run of governance failures or failed small IPOs erodes confidence, flows could slow at exactly the moment the market needs them. Regulators have described this as a matter of baseline trust. Expanding the capital market through outreach alone is not enough; investors must also believe that the companies they buy are genuine.