As investors debate whether artificial intelligence will boost or disrupt enterprise software companies, ServiceNow has delivered results that its chief executive described as a turning point.
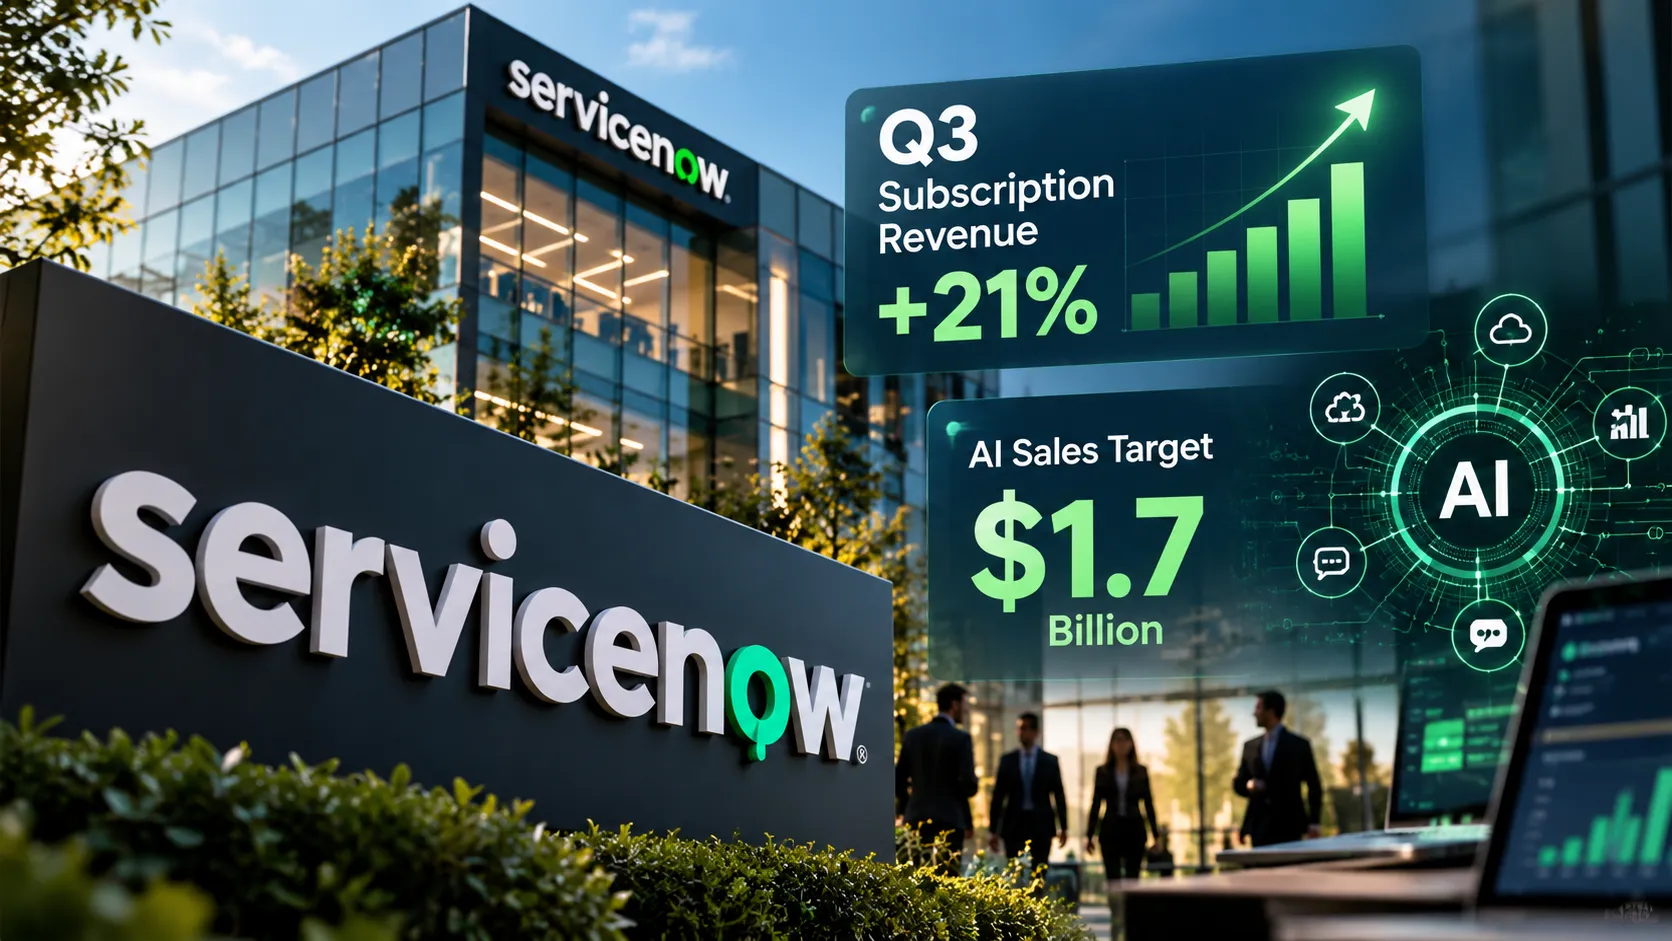
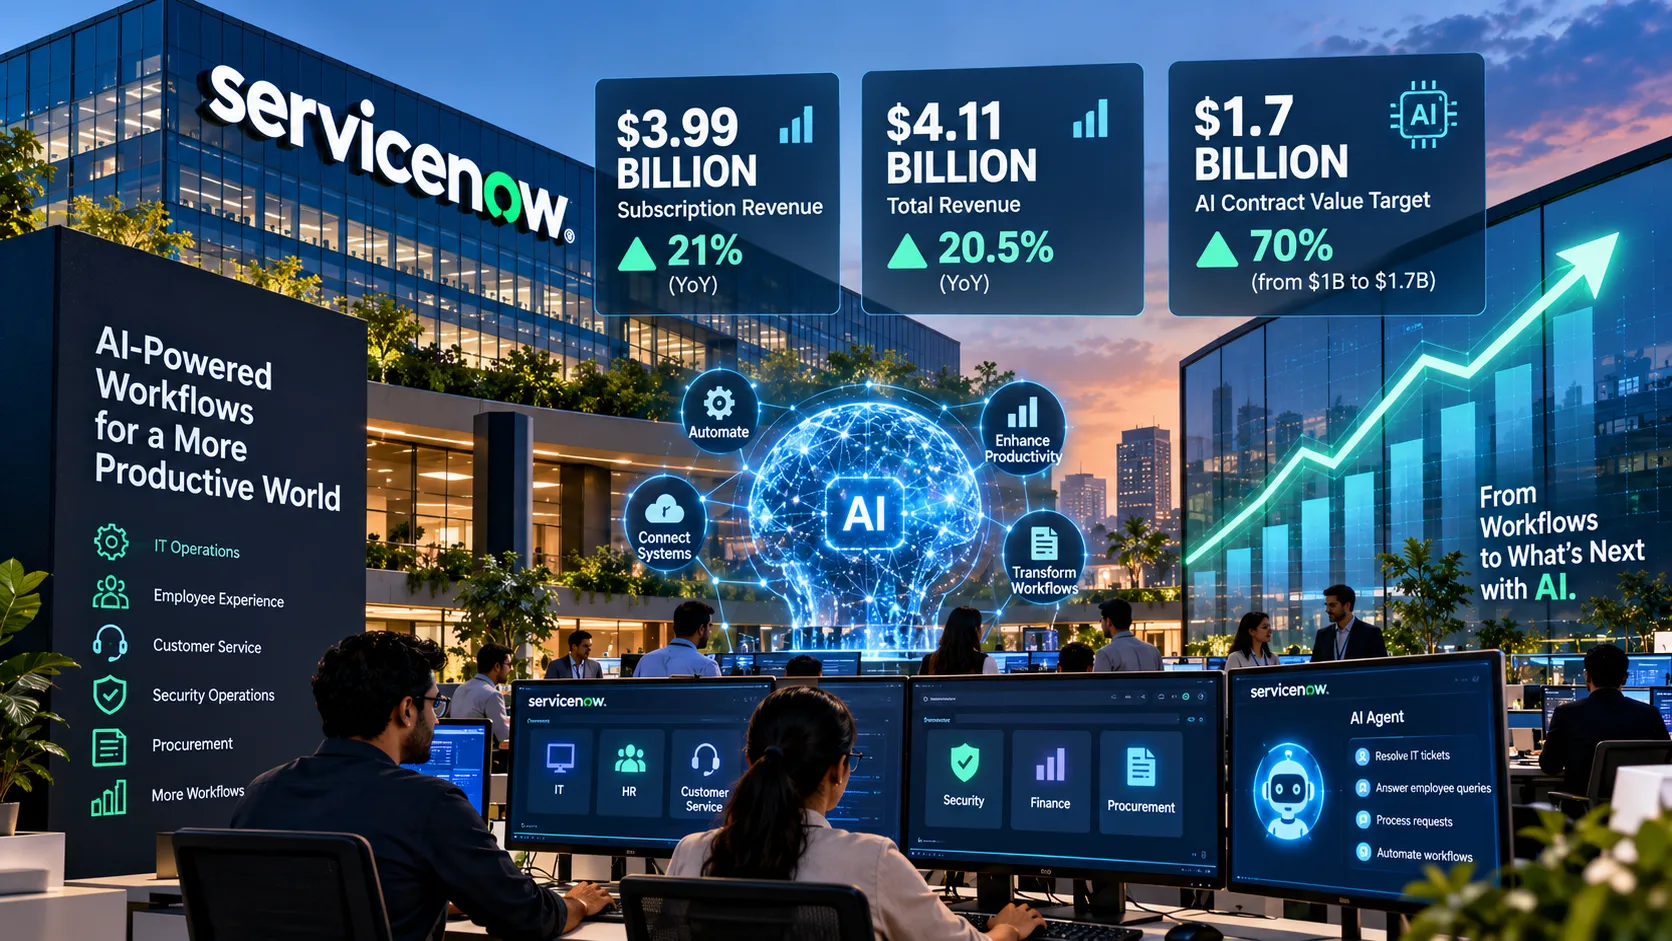
The Santa Clara, California-based company reported subscription revenue of $3.988 billion for the third quarter, up 21% from a year earlier, or 20.5% in constant currency, according to its earnings release on Wednesday, October 28. Total revenue rose 20.5% to $4.106 billion.
"This was more than another beat-and-raise quarter for ServiceNow, this was the inflection point for ServiceNow," said chairman and chief executive Bill McDermott. He said customers had validated the company's strategic relevance.
Strong forward indicators
Current remaining performance obligations (cRPO), which measure contracted revenue expected to be recognised over the next 12 months, rose 20.5% to $13.65 billion. Total remaining performance obligations increased 22% to $29.7 billion.
These figures are closely watched as indicators of future revenue growth for subscription software companies.
Profitability
ServiceNow's GAAP operating margin was 9.5%, with income from operations of $385 million. On a non-GAAP basis, which excludes items such as stock-based compensation, the operating margin was 32.5%, with income from operations of $1.338 billion.
The company raised its full-year non-GAAP free cash flow margin target by 100 basis points to 36%.
The AI story
The most significant part of the results concerned AI. ServiceNow raised its 2026 target for net new annual contract value from AI products for the second time this year, to $1.7 billion from $1 billion at the start of the year, an increase of 70%.
Year-to-date consumption of agentic AI in production rose more than 13 times from a year earlier. Agentic AI refers to AI systems that can carry out multi-step tasks autonomously, such as resolving IT support tickets, processing employee requests or managing customer service cases.
ServiceNow has positioned itself as a platform for orchestrating AI agents across enterprises, connecting different systems, data sources and workflows. Its strong AI growth suggests that businesses are moving beyond experimentation to deploying AI in production.
Raised guidance
ServiceNow raised its full-year 2026 subscription revenue guidance to $15.78 billion to $15.79 billion, representing 22.5% growth.
The AI disruption debate
Enterprise software companies have faced questions about whether AI will disrupt their business models. Some investors worry that AI agents could reduce the need for software seats, since fewer human users may be needed, or that AI-native competitors could displace established platforms.
ServiceNow's results suggest that, at least for now, established platforms with deep integration into enterprise workflows can benefit from AI by selling new capabilities to existing customers. The company has been shifting towards pricing models that reflect AI consumption, rather than relying solely on per-user subscriptions.
Competition
ServiceNow competes with Salesforce, Microsoft, SAP, Workday and other enterprise software providers, all of which are investing heavily in AI agents. The race to become the primary platform for enterprise AI is intense, and companies are seeking to differentiate through integration, data and industry-specific capabilities.
Microsoft, which reported results on the same evening, showed strong demand for its Copilot AI tools and Azure cloud services, highlighting the competition ServiceNow faces.
What it means for India
ServiceNow has a significant presence in India, with large engineering and operations centres in Hyderabad and Bengaluru. India is one of its most important talent hubs for product development.
Indian IT services companies are also major ServiceNow partners, helping clients implement and customise its platform. Strong demand for ServiceNow's AI products could create opportunities for Indian IT firms in implementation services, though AI automation may also reduce demand for some traditional IT support work.
The workflow platform
ServiceNow began as a provider of IT service management software, helping companies manage IT requests, incidents and changes. Over time, it has expanded into customer service, human resources, security operations, procurement and other business functions, positioning its platform as a system for managing workflows across an organisation.
The company's strategy is to use AI to automate these workflows. Its AI agents are designed to handle tasks such as resolving IT tickets, answering employee questions and processing customer requests, reducing the need for manual work. ServiceNow argues that its platform, which already holds data about how organisations operate, gives it an advantage in deploying AI effectively.
Pricing AI
One challenge for enterprise software companies is how to charge for AI. ServiceNow has introduced premium editions of its products that include AI capabilities, priced higher than standard editions. It has also explored consumption-based pricing for some AI features. The AI net new annual contract value target of $1.7 billion indicates that the company expects significant revenue from these products.
How customers respond to AI pricing will be important. Companies are willing to pay for AI if it delivers clear productivity gains, but they are also cautious about rising software costs.
The seat-based model debate
A broader concern for software companies is that AI agents could reduce the number of human users, threatening traditional seat-based pricing. If AI can do the work of several employees, companies may need fewer software licences. ServiceNow and other companies are adapting their pricing models to capture value from AI usage rather than only from the number of users.
What comes next
Investors will watch whether ServiceNow can sustain its AI momentum and convert its growing contract backlog into revenue. Its fourth-quarter results, along with guidance for 2027, will indicate whether the "inflection point" McDermott described translates into accelerating growth.
The Indian talent connection
ServiceNow, like many large American software companies, has a significant presence in India, with large engineering and operations teams in cities such as Hyderabad and Bengaluru. Indian IT services companies, including Infosys, TCS, Wipro and HCLTech, are major ServiceNow implementation partners, helping enterprises deploy its platform. As ServiceNow's AI products gain traction, demand for skilled professionals who can configure and integrate them is likely to grow, creating opportunities for Indian technology workers and service providers. Investors will watch whether ServiceNow's AI momentum continues into its next quarterly report.
For investors, the key question is whether ServiceNow's AI products can deliver sustained growth in contract value without eroding its traditional seat-based revenue. The company's confident tone suggests management believes the answer is yes, but competition from other software giants and AI-native startups will test that belief in the quarters ahead.