Swara Baby Products, a manufacturer of diapers and other disposable hygiene products that is majority-owned by FirstCry parent Brainbees Solutions, has received approval from the Securities and Exchange Board of India for an initial public offering of about ₹1,000 crore.
The offer will be split evenly between a ₹500 crore fresh issue of shares and a ₹500 crore offer for sale (OFS) by existing shareholders. SEBI issued its final observations on 6 October, about three months after the company filed its draft red herring prospectus in July.
The listing would give public investors direct access to a segment of the consumer economy that rarely appears on stock exchanges: the contract manufacturers that produce private-label and branded hygiene products for retailers and consumer companies.
Who is selling, and where the money goes
Brainbees Solutions, which owns 76.6 per cent of Swara, will sell shares worth ₹300 crore through the OFS. Co-promoter Anadya Bon Merchari LLP will sell shares worth ₹200 crore. The company is also considering a pre-IPO placement of up to ₹100 crore, which, if completed, would typically reduce the size of the fresh issue.
Of the proceeds from the fresh issue, ₹198.2 crore is earmarked for a new manufacturing facility in Madhya Pradesh. Another ₹100 crore will go towards repaying debt, and ₹27.5 crore will be invested in subsidiaries Solis Hygiene, Swara Hygiene and KAEHPL to reduce their borrowings. The remainder will fund potential acquisitions and general corporate purposes.
The allocation points to a company planning to grow capacity while cleaning up its balance sheet, a combination public investors generally favour in manufacturing businesses because it reduces financial risk while supporting future earnings.
The planned facility in Madhya Pradesh would add to Swara's manufacturing footprint in a state that has actively courted consumer-goods and packaging investment with land and incentive packages. Hygiene products are bulky relative to their value, so locating plants closer to large consumption centres in central and northern India can reduce freight costs, an important consideration in a business where margins depend on efficiency.
For Brainbees, the partial sale crystallises value from an investment that sits outside its core retail business while allowing it to retain a significant stake. FirstCry itself listed on Indian exchanges in August 2024, and the Swara IPO offers its shareholders a clearer view of the value of one of its manufacturing assets.
India's largest hygiene contract manufacturer
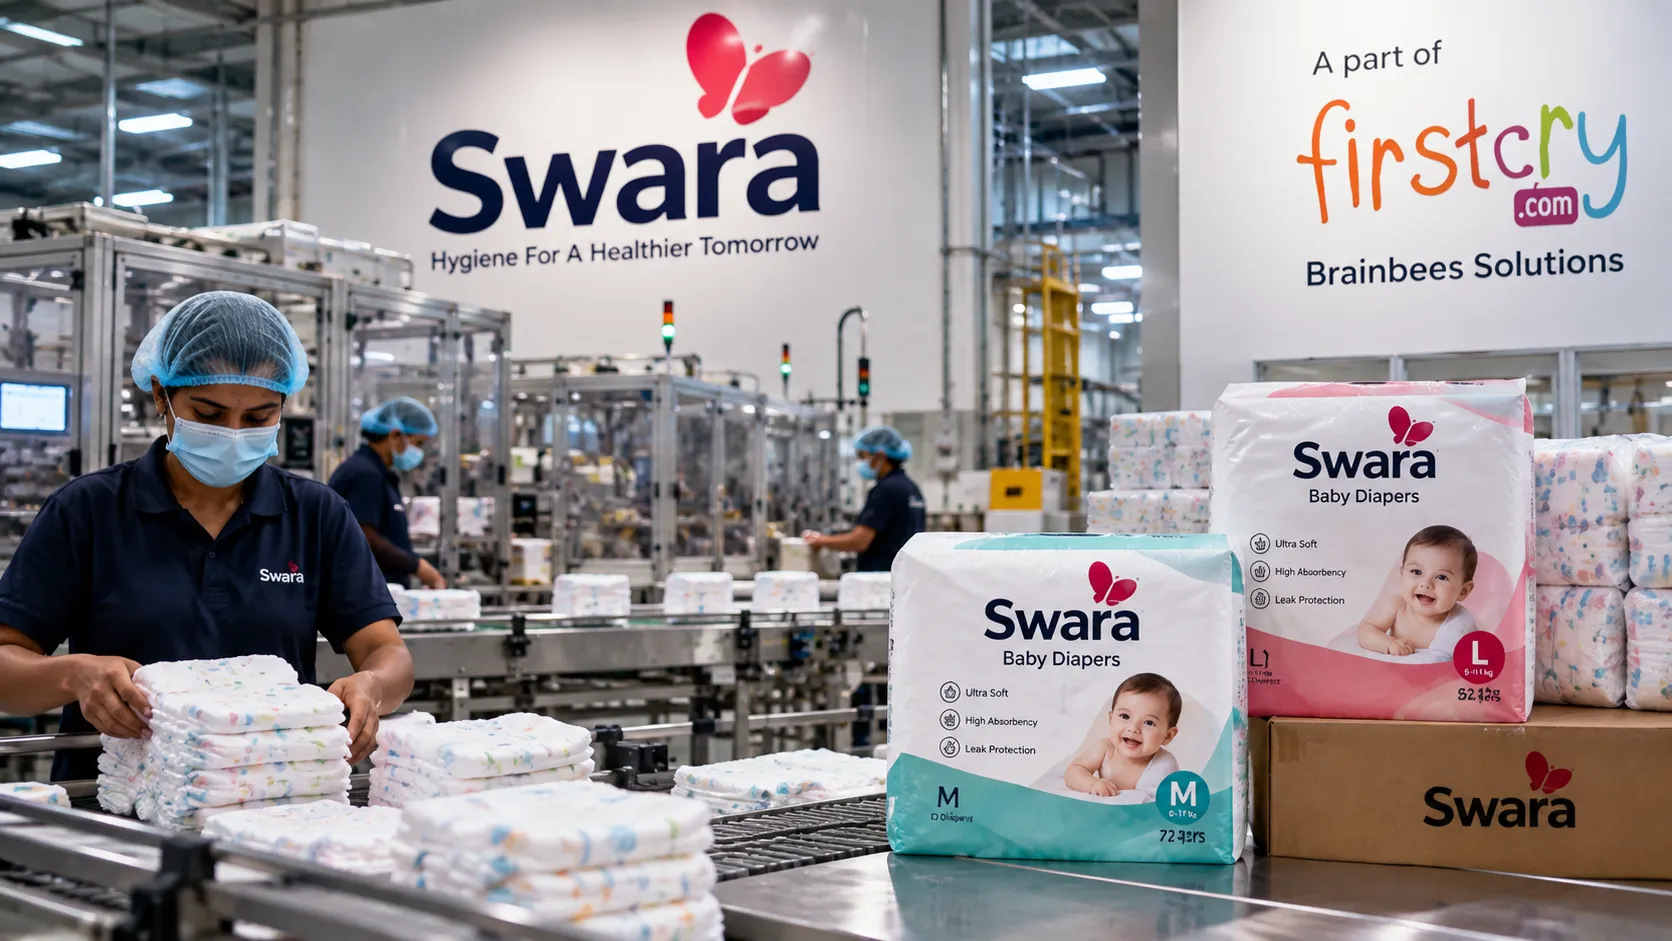
Founded in 2018, Swara makes disposable hygiene products across three segments: baby care, adult incontinence and feminine hygiene. It describes itself as India's largest hygiene contract manufacturer by value in FY25, with industry data in its filings placing its share at about 37 per cent of the contract-manufactured baby diaper segment and 36 per cent of adult diapers.
Its customers include Brainbees Solutions, which sells baby products under FirstCry's own labels, as well as pharmaceutical group Piramal Pharma and personal-care company Himalaya Wellness. In December 2025, Swara expanded into feminine hygiene by acquiring manufacturer KAEHPL.
The financial performance behind the IPO is solid. Operating revenue rose 23.4 per cent to ₹1,163 crore in FY26, while net profit increased 18.5 per cent to ₹95.6 crore, giving a net margin of a little over 8 per cent.
Contract manufacturing in consumer goods is a business of scale and reliability. Brands outsource production to avoid tying up capital in factories, while manufacturers compete on cost, quality and the ability to deliver large volumes consistently. Margins are typically thinner than those earned by brand owners, but customer relationships can be long-lasting and growth can be steady if the underlying categories expand.
Customer concentration is the obvious question for investors. A large share of Swara's revenue is likely to come from its parent, and the terms of related-party transactions will be closely examined when the red herring prospectus is filed. Diversifying its client base beyond Brainbees will be important for the company to earn a valuation independent of its parent's fortunes.
Riding demographic and category tailwinds
Swara's three categories are each supported by long-term trends. Diaper penetration among Indian infants remains low compared with developed markets, leaving room for growth as incomes rise. Adult incontinence products are a small but fast-growing segment as India's population ages and social stigma around the category gradually eases. Sanitary pad use has risen significantly over the past decade, supported by public health campaigns and wider retail availability.
Private labels add another tailwind. Retailers and e-commerce platforms, including FirstCry, increasingly sell their own brands in commoditised categories such as diapers and wipes, where they can offer lower prices and earn higher margins. Every new private label needs a manufacturer, and Swara has positioned itself as the supplier of choice for several of them.
Raw materials are the main swing factor in the business. Diapers and sanitary products rely on fluff pulp, super-absorbent polymers and nonwoven fabrics, several of which are linked to global commodity and petrochemical prices. Sharp moves in crude oil, such as those seen in recent months amid Middle East supply disruptions, can squeeze margins for contract manufacturers that cannot pass costs on to customers quickly.
Competition is also intensifying. Global consumer-goods majors manufacture at scale in India, and a number of domestic players supply private labels and regional brands. Swara's leadership position gives it purchasing power and operating experience, but it will need continued investment in capacity and product innovation, such as thinner, more absorbent designs and more sustainable materials, to hold that position.
The IPO will test investor appetite for a manufacturing-led story linked to a new-age consumer platform. Indian equity markets have been volatile in recent weeks, and recent listings have met a mixed reception. Swara's profitability and its use of proceeds for capacity and debt reduction may help it stand out from loss-making technology companies seeking listings, but pricing will be decisive.
Investors will also look for clarity on how Swara's relationship with FirstCry will evolve after listing. A clearly documented supply agreement, priced on arm's-length terms and with transparent volume commitments, would reassure minority shareholders that the company's earnings are not dependent on decisions made by its parent in the parent's own interest.
The company now has 12 months from the date of SEBI's observations to launch its offer. Timing will depend on market conditions, the outcome of any pre-IPO placement and the valuation its bankers believe public investors will support.