Oct 8 — Vesta, a start-up building modern software for mortgage lenders, has raised $30 million in a round led by Conversion Capital, as lenders increasingly adopt AI agents to automate the slow and costly process of originating home loans.
The round included participation from two of the mortgage industry's significant lenders, Pennymac and New American Funding, as well as Citi Ventures and Andreessen Horowitz. The new funding takes Vesta's total capital raised to $85 million.
The investment comes as the company reports rapid growth: revenue increased 12-fold over the past year, and its platform now supports more than $100 billion a year in loan volume.
Key facts at a glance
• Round: $30 million, led by Conversion Capital
• Participants: Pennymac, New American Funding, Citi Ventures, Andreessen Horowitz
• Total raised: $85 million
• Founded: 2020, by Mike Yu (CEO) and Devon Yang
• Growth: revenue up 12-fold year on year
• Scale: platform supports more than $100 billion a year in loans
• Market share: below 5%
• Industry pain point: about 40 days and $11,000 to close a US mortgage
A slow, expensive process
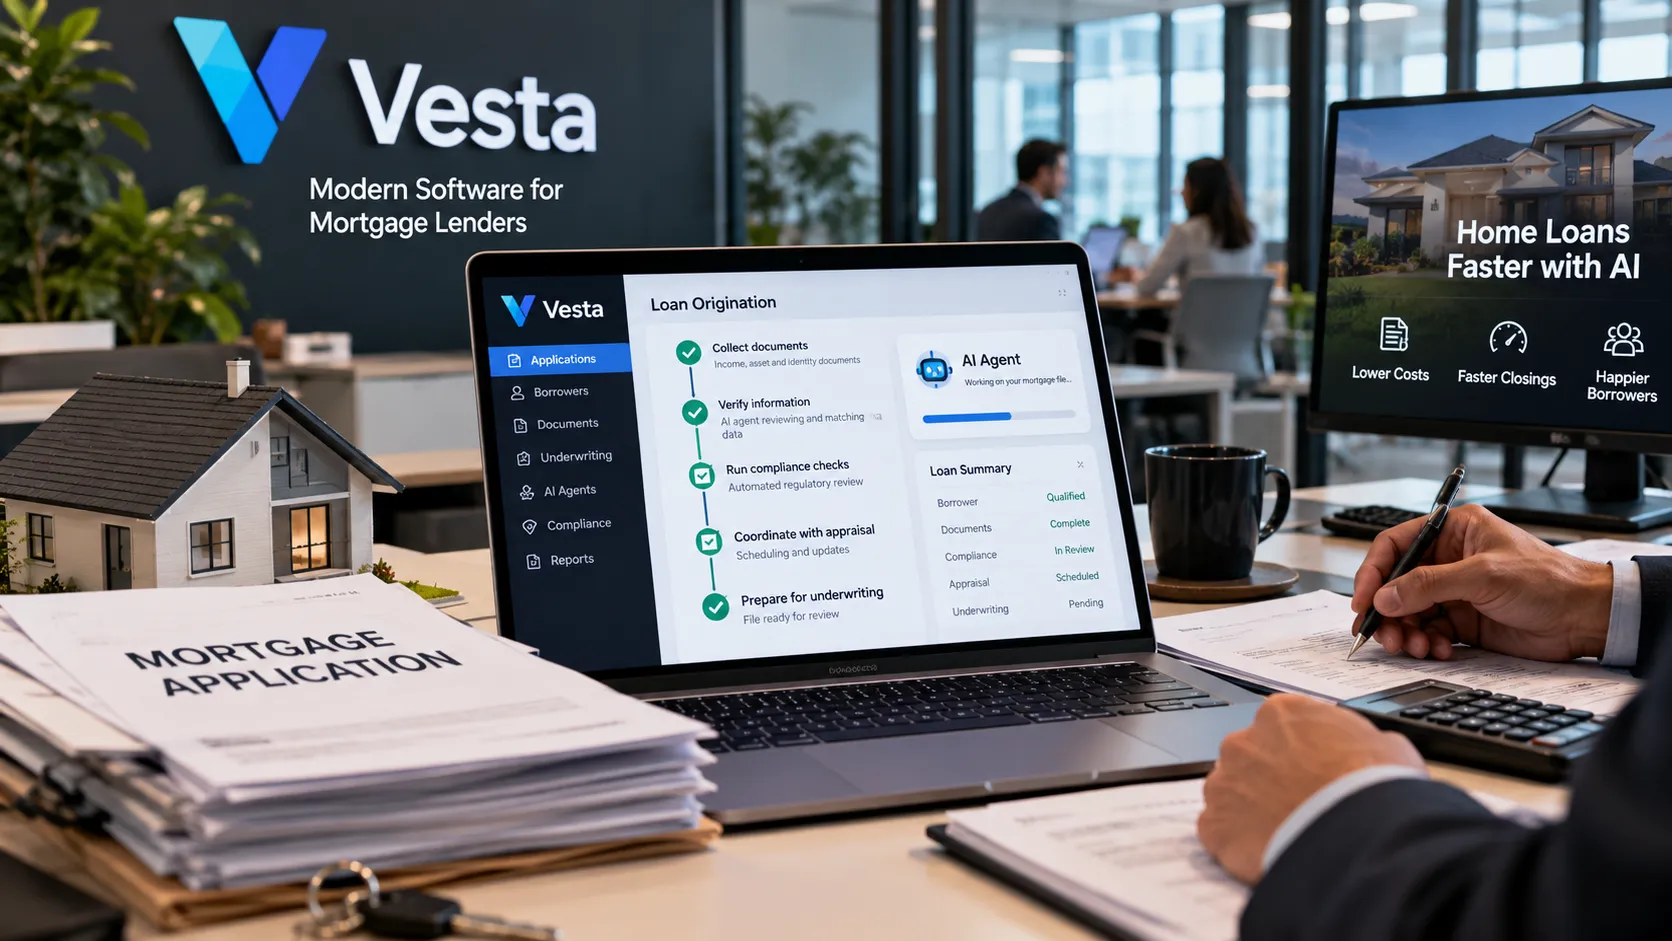
Getting a mortgage in the United States remains a remarkably cumbersome experience. Closing a typical loan takes about 40 days and costs lenders around $11,000, according to figures cited by the company. Much of that time and cost goes into manual tasks: collecting documents, verifying income and employment, checking compliance requirements, coordinating with appraisers and title companies, and moving files between teams.
The software systems that lenders use to manage this process — known as loan origination systems — are often decades old. They were built for a world of paper files and manual review, and lenders have typically layered additional tools on top of them to fill gaps, creating complex and expensive technology stacks.
Vesta's pitch is to replace that legacy infrastructure with a modern, cloud-based platform designed for automation from the ground up. By structuring data and workflows in a way that software can understand, the company aims to allow lenders to automate large parts of the origination process.
The AI agent breakthrough
Vesta was founded in 2020 by Mike Yu, its chief executive, and Devon Yang. The company spent its early years building core infrastructure for lenders, but its growth accelerated as advances in AI made it possible to automate tasks that previously required human judgment.
The company has credited Anthropic's Claude Sonnet 4.5 model as a breakthrough moment, enabling AI agents that can reliably carry out multi-step tasks within the mortgage workflow — such as reviewing documents, identifying missing information and preparing files for underwriting. For an industry where errors can lead to regulatory penalties and financial losses, reliability is critical, and improvements in model capability have made lenders more willing to deploy AI in production.
Lenders as investors
The participation of Pennymac and New American Funding is notable. When lenders invest in a software provider, it signals confidence not only in the product but in its long-term importance to their operations. It also aligns incentives: lenders that use Vesta's platform have a stake in its success and in shaping its development.
Citi Ventures' involvement adds the perspective of one of the world's largest banks, while Andreessen Horowitz brings deep experience in fintech and enterprise software. Conversion Capital, which led the round, focuses on financial services and technology businesses.
Room to grow
Despite its rapid growth, Vesta still holds less than 5% of the market, according to the company. The loan origination software market is dominated by established providers, most notably ICE Mortgage Technology, whose platform is used by a large share of US lenders. Other competitors include newer platforms such as Xpanse.
Displacing incumbent systems is difficult. Lenders are cautious about changing core infrastructure, which requires migrating data, retraining staff and ensuring compliance with complex regulations. However, the cost pressures of the mortgage industry — where volumes fluctuate sharply with interest rates — give lenders strong incentives to find efficiencies.
The promise of AI agents adds urgency. Lenders that can process loans faster and at lower cost can offer better rates and service, giving them an advantage in a competitive market. That has encouraged some lenders to look at modern platforms that can support automation more effectively than legacy systems.
The timing of the raise is also notable. Mortgage volumes in the United States are sensitive to interest rates, and lenders that invested in automation during quieter periods tend to be better positioned when activity picks up.
Where AI agents fit in a mortgage
A mortgage file involves dozens of documents — pay slips, tax returns, bank statements, identity documents, appraisals, title reports and disclosures — each of which must be collected, checked and reconciled. Much of this work is repetitive but requires attention to detail: confirming that income figures match across documents, spotting missing pages, flagging unusual deposits, and checking that disclosures were sent on time.
These are the kinds of tasks where AI agents can make a difference. An agent can review documents as soon as they arrive, request missing items from borrowers, prepare summaries for underwriters and track deadlines. Human staff remain responsible for final decisions, but they spend less time on routine checks. For lenders, the result can be shorter closing times, lower costs per loan and the ability to handle surges in volume without hiring large temporary teams.
A template for vertical AI
Vesta's story reflects a broader trend in enterprise technology. Some of the fastest-growing AI companies are not building general-purpose models but applying those models to specific industries with complex workflows, heavy regulation and high costs. Mortgage lending, insurance, healthcare administration and legal services are all prime targets.
For founders, including the many Indian and Indian-origin entrepreneurs building enterprise software for US markets, Vesta's growth illustrates the opportunity in combining deep domain expertise with modern AI. For investors, it shows how improvements in foundation models can quickly translate into commercial traction for companies that have already built the underlying infrastructure.
With fresh capital, Vesta plans to expand its platform and win more lenders. If it can cut the time and cost of getting a mortgage significantly, the benefits would extend well beyond lenders — to the millions of households that navigate the process each year.